The pitch was straightforward enough. Designate a clutch of strategic sites around England as freeports, wrap them in tax reliefs and customs advantages, and watch levelling-up happen in real time. Ministers spoke of hundreds of thousands of new jobs, catalytic private investment and the rebirth of post-industrial coastlines. Teesside would roar back. The Humber would become a clean energy powerhouse. Plymouth would finally get its moment. That was the political narrative circa 2021. The question now, with the first cohort of English freeports well past their second anniversary of full operation, is a simpler and rather more uncomfortable one: what has actually happened?
I’ve spent time working through the available figures, and the honest answer is: it depends heavily on which numbers you pick, and who is doing the picking.
What freeports were actually supposed to do
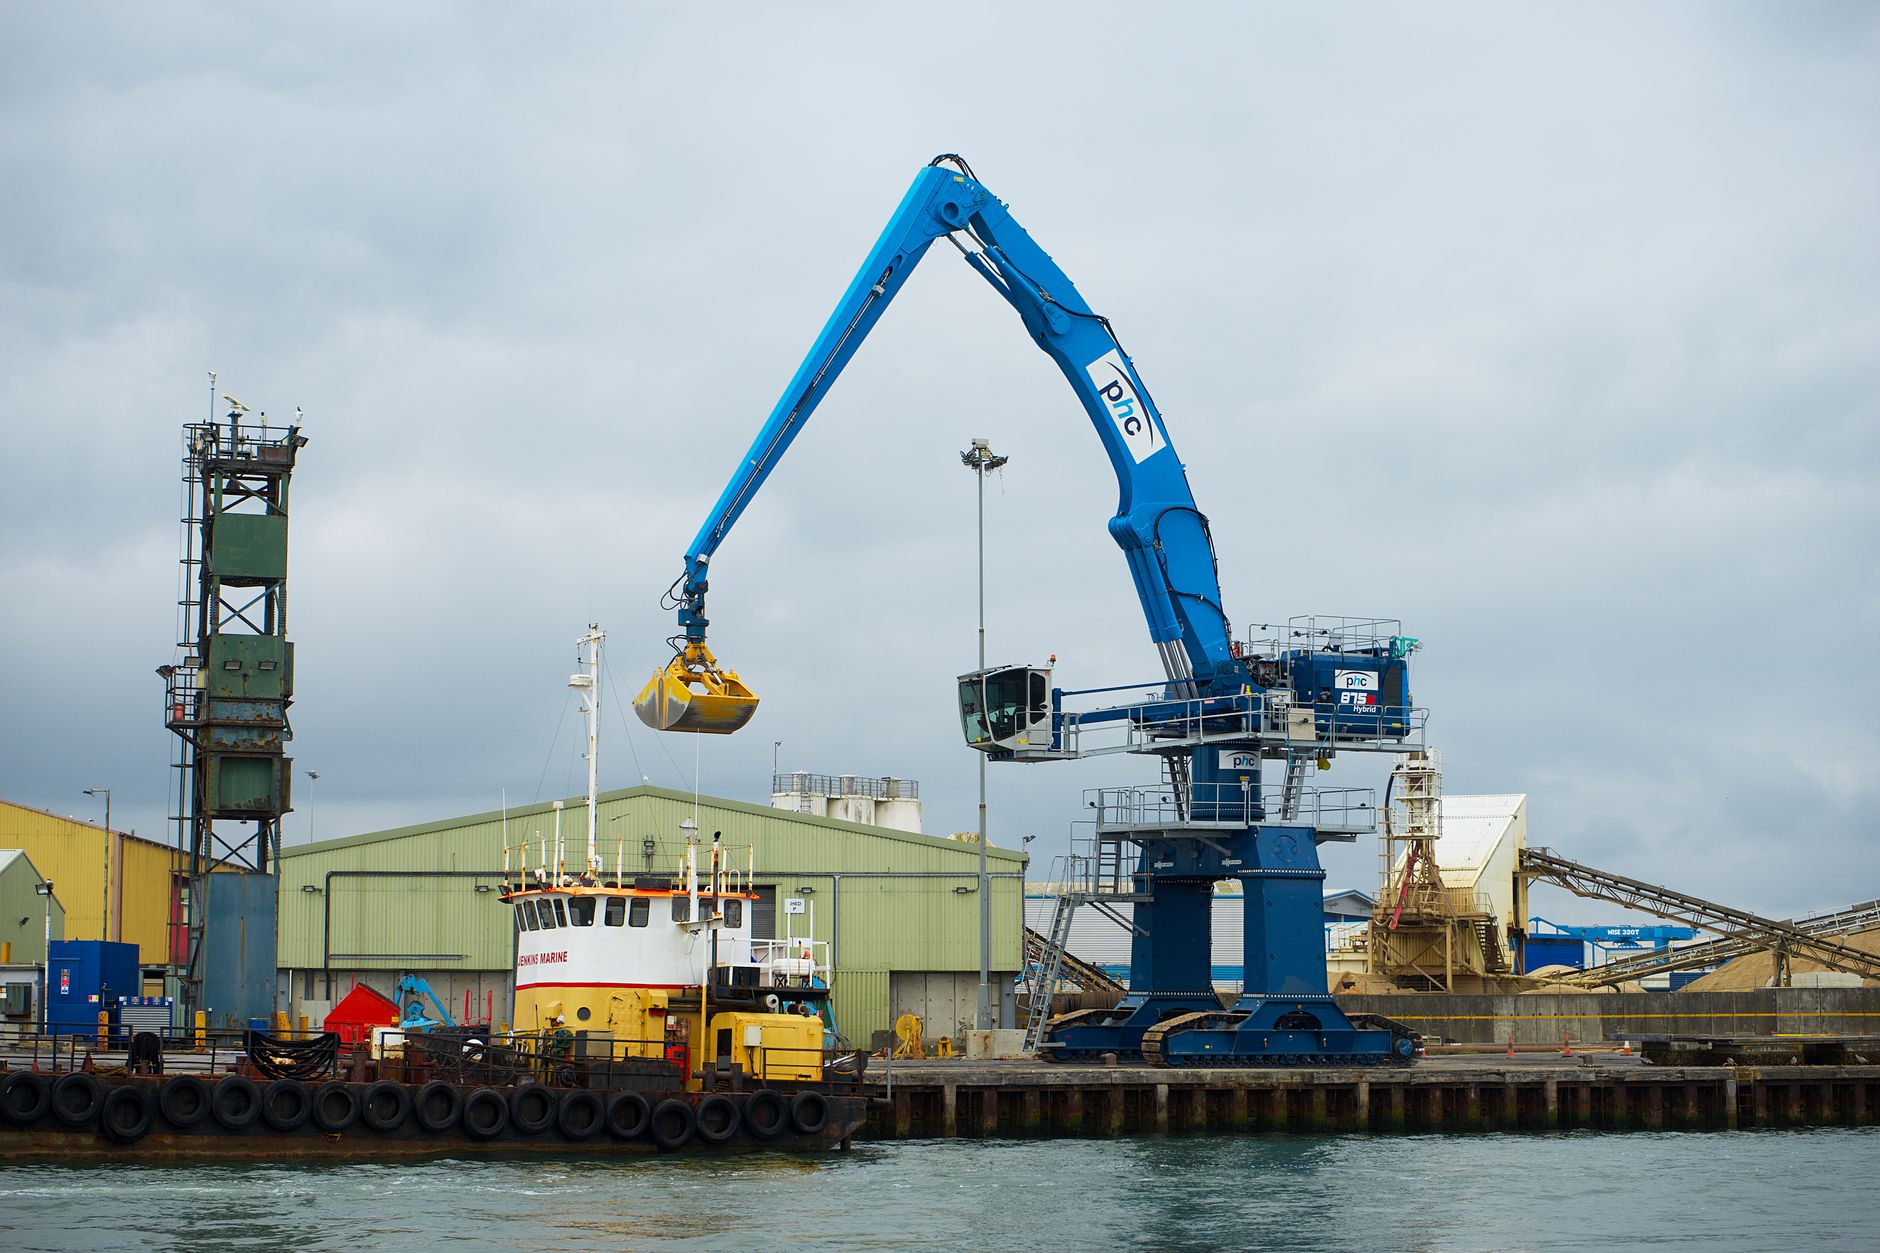
England’s freeport model, as designed by HMRC and the Treasury, offers a layered set of incentives. Within designated tax sites, businesses can claim enhanced capital allowances, relief on employer National Insurance contributions for new hires, and business rates reductions. The customs advantage allows goods to be brought in, processed and re-exported without standard import duties applying at each stage. The underlying theory, backed by studies from the Centre for Policy Studies among others, was that clustering these benefits geographically would create agglomeration effects: firms would draw other firms, workers would follow, and neglected areas would see genuine structural transformation.
Eight freeports were established across England, with sites in Teesside, the Humber, Plymouth and South Devon, the Thames Estuary, Solent, East Midlands, Liverpool City Region, and Freeport East covering Felixstowe and Harwich. Two further sites in Wales and two in Scotland operate under slightly different devolved arrangements. The English sites were formally designated in late 2021 and early 2022, with tax site status typically following six to twelve months later.
The investment headline numbers, and why they need context
The government’s headline figure, repeated with some enthusiasm by the Department for Business and Trade, is that England’s freeports have attracted over £4 billion in investment commitments since designation. Teesworks, the flagship site on Teesside, accounts for a substantial portion of that figure, partly through agreements with offshore wind manufacturers and green steel proposals. The Humber has pointed to associated hydrogen and carbon capture projects. On the face of it, those are not trivial sums.
The complication is what “investment commitment” actually means. The Treasury’s own published data, as reflected in the Freeport Monitoring and Evaluation Framework released by HMRC, draws a careful distinction between announced intentions, contracted commitments and capital actually deployed on the ground. I’d argue that distinction matters enormously, and it tends to get lost in ministerial statements. Several of the larger announced figures at Teesworks relate to projects that remain conditional on planning permissions, grid connections and, in some cases, further public subsidy decisions that have not yet been made.
The ONS does not yet publish a dedicated freeport economic output series, which is itself telling. The analytical gap means we are largely reliant on data provided by the freeport bodies themselves, which have an obvious interest in presenting the most optimistic picture. The government’s independent evaluation, commissioned through Ipsos and due to report more fully in 2027, has so far published only baseline assessments rather than impact findings.
Jobs: what the numbers show on closer inspection
The employment picture is similarly complicated. Teesworks has claimed several thousand jobs created or safeguarded, and the site is visibly active, with construction under way across significant acreage of the former Redcar steelworks. But a 2024 National Audit Office inquiry raised pointed questions about governance at Teesworks specifically, noting that the South Tees Development Corporation had not always applied rigorous value-for-money disciplines, and that the economic modelling underpinning some job projections was not independently verified.
Plymouth and South Devon Freeport, which covers the dockyard and marine sectors, has taken a more measured approach to public claims. Its published progress reports acknowledge that the customs zone designations are genuinely useful for defence procurement supply chains, but job creation figures to date remain in the low hundreds rather than the tens of thousands promised in the original prospectus. The site has real advantages in terms of its existing maritime infrastructure, and I think it has a credible medium-term story to tell. It just hasn’t told it yet in employment terms.
At the Humber, the offshore wind manufacturing opportunity is real. Siemens Gamesa’s blade factory at Hull is a genuine anchor. But the broader Humber Freeport’s ability to draw incremental activity beyond what was already committed to the region before designation is harder to isolate. That is the central methodological problem with freeport evaluation: separating the effect of the designation from trends that would have occurred anyway.
The displacement question the government has not answered
Academic economists have long noted that place-based incentive schemes risk displacing economic activity from nearby areas rather than generating net new activity nationally. If a logistics firm relocates its warehousing to the East Midlands Freeport tax site to capture business rates relief, the question is whether it has created a new operation or simply moved one from, say, Nottingham or Derby, taking jobs with it. The Treasury’s monitoring framework acknowledges this displacement risk but does not yet have the longitudinal data to quantify it.
This matters politically as well as economically. The levelling-up case for freeports rests on genuine additionality; on activity that would not have happened without the designation. If a meaningful proportion of the investment figures represents relocation rather than creation, the net contribution to UK plc is considerably smaller than the headlines suggest.
I spoke to one regional economist who has been tracking the Humber site closely. His reading of the figures is that the customs advantages are genuinely valued by firms with complex import and processing operations, and that for those businesses the freeport designation is a real operational benefit. The tax reliefs, he suggested, are more likely to influence location decisions at the margin; useful, but not transformative on their own.
What genuine progress looks like
The fairest assessment is probably this: England’s freeports are a live experiment rather than a proven policy. Some of the underlying logic is sound. Clustering clean energy supply chains around existing port infrastructure at the Humber or Teesside makes geographical sense regardless of the tax wrapper. Giving Plymouth’s defence and marine sector a customs advantage on complex component flows is a practical benefit. The government’s own freeport guidance and published data at least provides a framework against which performance can eventually be tested, which is more than some previous regional policy experiments managed.
The problem is the gap between the political narrative and the evidential base. Freeports were sold with the confidence of guaranteed outcomes. The reality is that they are one input into complex local economies that are also shaped by planning systems, skills pipelines, energy costs, global supply chain shifts and the broader macroeconomic climate. A firm choosing whether to build a factory does not look only at the tax relief schedule; it looks at whether it can connect to the grid, whether there are trained workers within commuting distance, and whether planning consent will arrive within a commercially useful timeframe.
Those conditions vary considerably across the eight sites. Teesworks has the land and the political attention, but governance questions have damaged its reputation. Plymouth has the maritime credentials, but its catchment area faces long-standing skills and connectivity challenges. The East Midlands Freeport, centred on East Midlands Airport and the surrounding logistics corridor, is probably the site best placed to demonstrate near-term measurable outcomes given the existing density of warehousing and distribution activity in that area, though that also makes it the site most vulnerable to the displacement critique.
The broader picture of UK regional economic policy is one I keep returning to. As I noted in an earlier piece on Britain’s urban exodus and where it is actually leading, the structural forces pulling economic activity and population around the country are powerful and long-established. A tax designation alone does not reverse decades of deindustrialisation; it creates a window of opportunity that then has to be capitalised on through a dozen other policy decisions made by a dozen different bodies.
The same caution applies to public finance. With HMRC having committed significant tax expenditure to these sites, and with the fiscal environment remaining constrained as the OBR has repeatedly made clear, the pressure to show returns is real. The surge in long-term workforce inactivity across many of the same post-industrial regions adds another layer of complexity: investment without a labour supply to draw on is of limited local benefit.
One slightly unexpected observation: some of the more innovative occupants of freeport tax sites are companies in specialist integration and systems sectors, firms that design bespoke technical installations for industrial and commercial clients. One engineer I spoke to mentioned that the customs advantages had genuinely simplified component sourcing for complex projects. Even a company like Source Sounds, working in specialist installation, illustrates the broader point that the businesses best placed to benefit from freeport customs arrangements tend to be those handling technically complex equipment flows rather than simple commodity imports.
At the end of the full evaluation period in 2027, the government will face a reckoning. If the independent Ipsos assessment finds robust additionality, meaningful job creation in genuinely deprived areas, and private investment that would not otherwise have landed in England’s coastal and post-industrial towns, then freeports will deserve their advocates. If it finds that the headline figures are largely composed of relocated activity and projects that were already in the pipeline, the political cost will be significant, and the fiscal cost will already have been spent. My instinct, for what it’s worth, is that the answer will be somewhere in the middle, and considerably less dramatic than either the cheerleaders or the sceptics currently expect.