The phrase “levelling up” was buried so quietly that most people missed the funeral. It faded from government briefings somewhere around 2023, replaced by a more cautious vocabulary of “regional growth” and “integrated settlements”. But the underlying ambition, shifting genuine economic power away from London and into England’s great regional cities, has not disappeared. It has simply become harder to measure, easier to spin, and more contested by the week. The question worth asking in 2026 is a blunt one: is UK regional economic devolution actually working, or are we watching a sophisticated redistribution of the same structural inequality dressed up in a mayoral sash?
What the inward investment figures actually say
Start with the numbers that boosters reach for first. Greater Manchester secured over £1.3 billion in foreign direct investment commitments in 2024 and 2025, according to MIDAS, its inward investment agency. The West Midlands Combined Authority pointed to roughly 30,000 new jobs created through investment deals since Andy Street’s tenure began. Leeds City Region has attracted significant financial services relocations, partly as a consequence of post-Brexit operational restructuring by major banks spreading headcount north.
These are not trivial figures. But context matters enormously. London attracted more than £16 billion in FDI in the same period, according to the Greater London Authority’s investment data. The capital’s share of total UK professional and financial services output has barely shifted in a decade. The productivity gap, measured as output per hour worked, between London and the next most productive English region has actually widened slightly since 2019, according to ONS regional accounts data. So the investment headlines from Birmingham and Manchester are real, but they exist against a backdrop where London’s gravitational pull has not meaningfully weakened.
What mayoral combined authorities can and cannot do
The devolution settlement for England’s Mayoral Combined Authorities has expanded considerably. Greater Manchester now has an integrated transport and spatial planning function. The West Midlands has control over adult education budgets and some housing land. South Yorkshire, Tees Valley and the West of England all hold investment funds of varying sizes. The recent round of “trailblazer” devolution deals, signed in 2023 and extended since, gave Manchester and the West Midlands something closer to a single funding settlement rather than a patchwork of ring-fenced grants.
I’ve read through several of these settlement documents, and the honest impression is that they represent meaningful administrative progress without yet representing a transfer of the kind of fiscal power that would actually shift economic geography. Mayors can direct skills funding; they cannot set local income tax rates. They can approve a spatial development strategy; they cannot override national planning policy in the way a regional assembly with primary legislative powers could. The comparison with German Länder or even the Scottish Parliament, which has partial income tax variation, is instructive. English metro mayors remain, for now, relatively well-resourced administrators rather than genuine sub-national governments.
This matters for the productivity question because the evidence on what actually drives regional convergence, from studies of Italy’s Nord-Sud divide to comparisons between German regions, consistently points to fiscal autonomy, labour market flexibility and long-term infrastructure investment as the critical levers. English devolution, as currently constituted, touches some of these levers lightly rather than gripping them firmly. My reading of the evidence is that we have built an impressive scaffolding around a structure that has not yet changed its foundations.
Infrastructure spend: what HS2’s collapse revealed
The cancellation of the northern leg of HS2, confirmed in 2023 and now settled as a political fact rather than an ongoing debate, did genuine damage to the credibility of the regional rebalancing project. Birmingham Curzon Street is being built. Manchester Piccadilly is not getting its new station. The Treasury’s own analysis, leaked at the time, suggested the connectivity premium from linking major northern cities was the precise mechanism by which agglomeration benefits might spread. Without it, Manchester and Leeds remain well-connected to London but poorly connected to each other relative to what the plan promised.
The government’s Network North package, the replacement offer involving upgraded existing rail lines, has proceeded slowly. Some schemes are welcome. None of them replicate the transformative connectivity effect that the full HS2 network was modelled to deliver. Transport economists at the University of Leeds have been particularly clear-eyed about this, noting that journey time improvements between Manchester and Leeds remain modest on the current trajectory. For a productivity rebalancing story to hold, the physical infrastructure has to knit regional labour markets together. At present, it is doing so incrementally.
Where the case for optimism is genuinely strong
None of this is to say nothing has changed. Birmingham’s post-Commonwealth Games property and commercial investment pipeline has been real, if uneven. Manchester’s MediaCityUK cluster has grown into a genuine alternative hub for broadcasting and digital media, with the BBC, ITV and a range of tech employers representing something more than tokenistic relocation. Channel 4’s Leeds presence, now several years established, has brought production talent and spending power to the city in ways that were not previously there.
The skills picture is also shifting, slowly. Adult education budget devolution means that combined authorities can now align skills provision more tightly with local employer demand. In the Black Country and Solihull, this has produced some genuinely interesting partnerships between further education colleges and advanced manufacturing employers. It is exactly the kind of institutional alignment that regional economists argue is essential for sustained productivity growth, and it is happening in places it was not happening a decade ago.
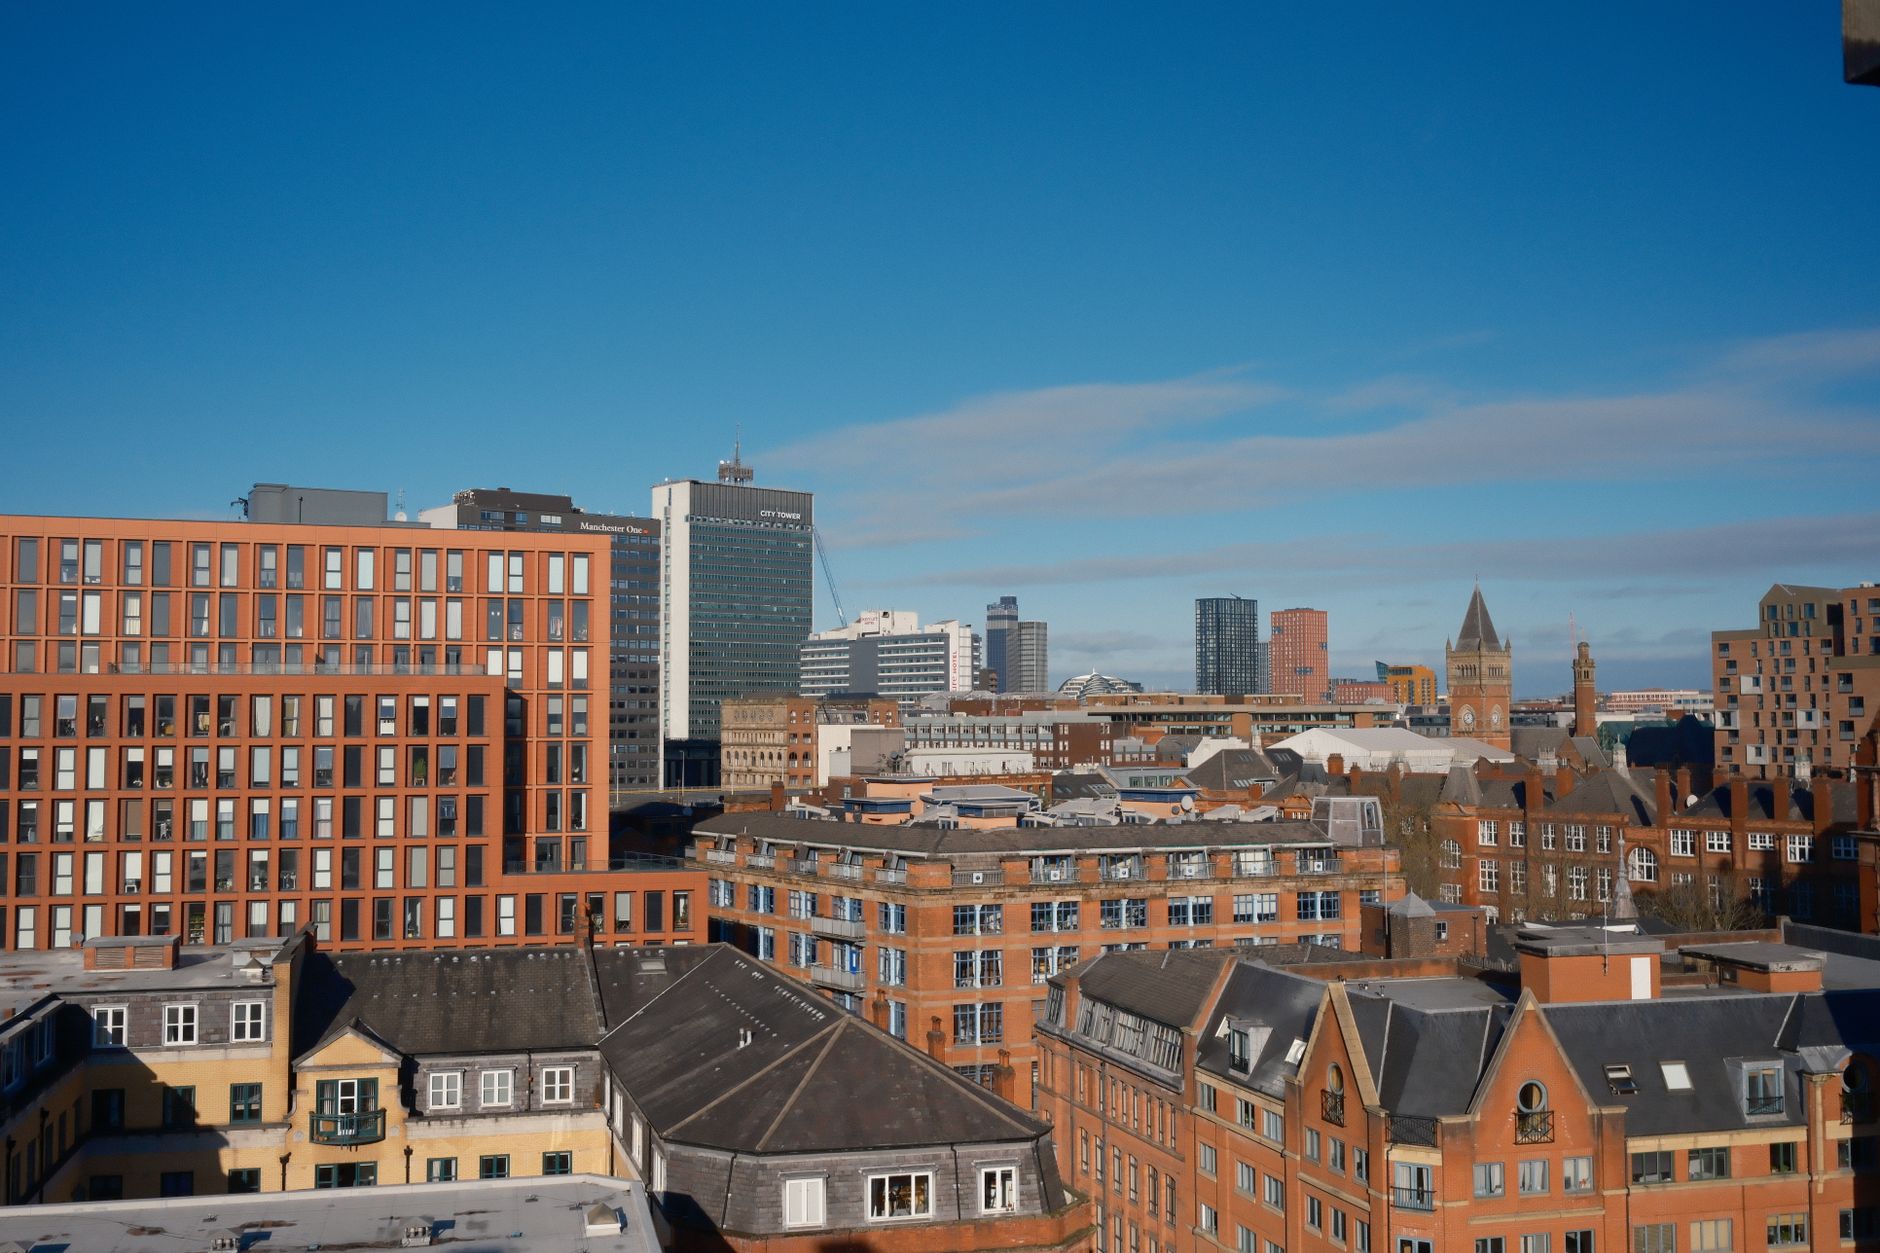
The urban planning transformation underway in cities like Manchester is also part of this picture, as denser, better-connected neighbourhoods raise the quality of life metrics that influence where younger workers choose to settle. And where people choose to live is, in the long run, where economic activity clusters. This is where I’d argue the optimists have a point that deserves to be taken seriously, even if the aggregate data remains stubbornly cautious.
The workforce question no one wants to answer directly
Regional economic rebalancing is also inseparable from the labour market, and the labour market is where some of the most uncomfortable data sits. The decline of middle-management roles is a national phenomenon, but its effects are geographically concentrated. The business services and professional sector jobs that once anchored Leeds, Sheffield and Birmingham’s middle-income workforce have been eroded by automation and restructuring in ways that London’s financial services concentration has partially insulated the capital from. The argument that devolution creates the conditions for new high-wage jobs to replace these losses is theoretically coherent; the evidence that it is happening at scale is not yet there.
There is also the question of what happens to workers who cannot simply retrain for digital roles, a challenge that is particularly acute in older industrial towns that sit outside the combined authority cores. The combined authorities are, structurally, city-focused. The towns that surround them, places like Rochdale relative to Manchester, or Wolverhampton relative to Birmingham’s gleaming new commercial quarter, often feel the political narrative of renaissance but see less of its economic benefit directly. This is redistribution of inequality more than its elimination.
So is the gap closing?
Honestly: not yet, not in the headline productivity numbers. The structural case for why it eventually should is coherent, and the institutional groundwork laid by the Mayoral Combined Authority model is more substantial than its critics acknowledge. But the fiscal powers remain too limited, the infrastructure investment too patchy after HS2’s truncation, and the timeline too short for any honest observer to declare victory. UK regional economic devolution in 2026 is a work in progress, which is a more encouraging verdict than it might sound, so long as the work actually continues.