Category: General News

  • The Quiet Crisis in Britain’s Volunteer Fire Services: How Rural Communities Are Being Left to Burn

    The Quiet Crisis in Britain’s Volunteer Fire Services: How Rural Communities Are Being Left to Burn

    There is a fire station in a market town in Shropshire that has been without a full crew for eleven months. The appliance sits there, polished and ready, but on any given weekday afternoon there are not enough retained firefighters available to take it out safely. This is not an anomaly. It is, I’m afraid, the texture of ordinary life across vast stretches of rural Britain in 2026, and the people responsible for fixing it have not yet managed to explain why they haven’t.
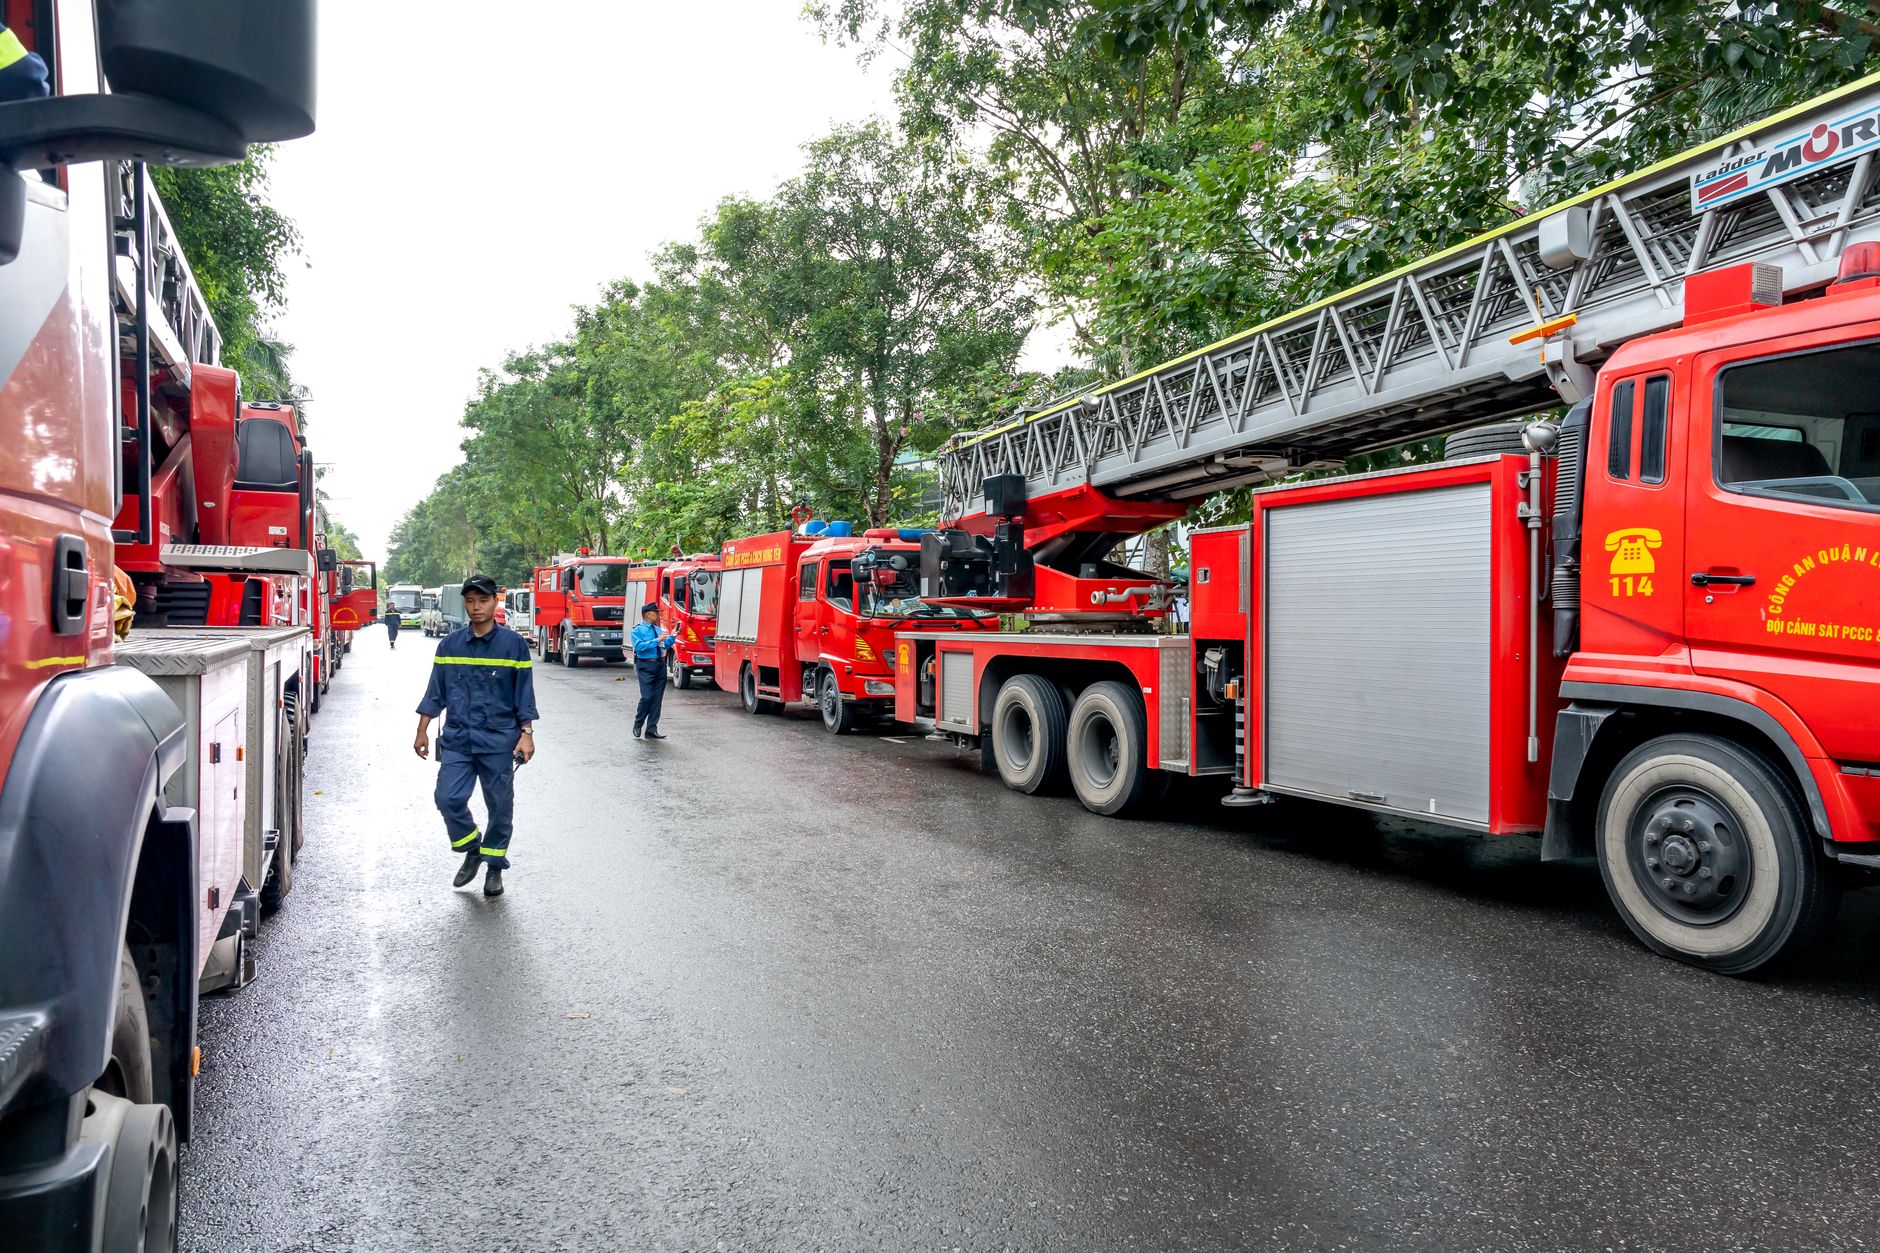
    Rural fire station with appliance visible, illustrating the retained firefighters crisis in the British countryside
    Photo by Quang Nguyen Vinh on Pexels

    Retained firefighters, also called on-call firefighters, are the backbone of fire and rescue cover outside Britain’s cities. According to the Home Office’s own workforce statistics, on-call staff make up roughly 36 per cent of the total fire and rescue workforce in England. In Scotland and Wales, the proportions in rural areas are higher still. Strip them out and you lose coverage for somewhere between 60 and 70 per cent of the country’s landmass. That is not a footnote. That is a structural fact.

    Why the numbers are collapsing

    The retained firefighters crisis did not arrive suddenly. It has been building for a decade, driven by a set of economic and social changes that interact badly with the specific demands of on-call service. To respond to a shout, a retained firefighter must be able to reach their station within a set time, typically four minutes. In a world where employment has concentrated in towns and cities, where broadband has still not reached many villages, and where the cost of housing has pushed younger workers further from rural centres, the pool of people who live or work close enough to a rural station has been quietly shrinking.

    Then there is the employer problem. Retained firefighters are not employed full-time by their fire service; they are paid a retaining fee and a turnout fee per incident. Their primary employer, if they have one, must be willing to release them at short notice. Increasingly, employers are not. The gig economy, zero-hours contracts, and the general erosion of workplace flexibility have made it functionally impossible for many workers to commit to on-call duties. I spoke to one retained crew manager in mid-Wales who told me he had lost four of his best people in eighteen months, not because they lost interest but because their employers simply refused to accommodate the interruptions.

    What underfunding actually looks like on the ground

    Fire and rescue authorities in England have faced cumulative real-terms funding cuts of around 30 per cent since 2010, according to the Local Government Association. The headline number obscures what that means operationally. It means recruitment campaigns that never launch because there is no budget. It means training programmes that are delayed or shortened. It means the retention payment, which has not risen meaningfully in years, failing to keep pace with what people can earn in any number of other flexible roles.
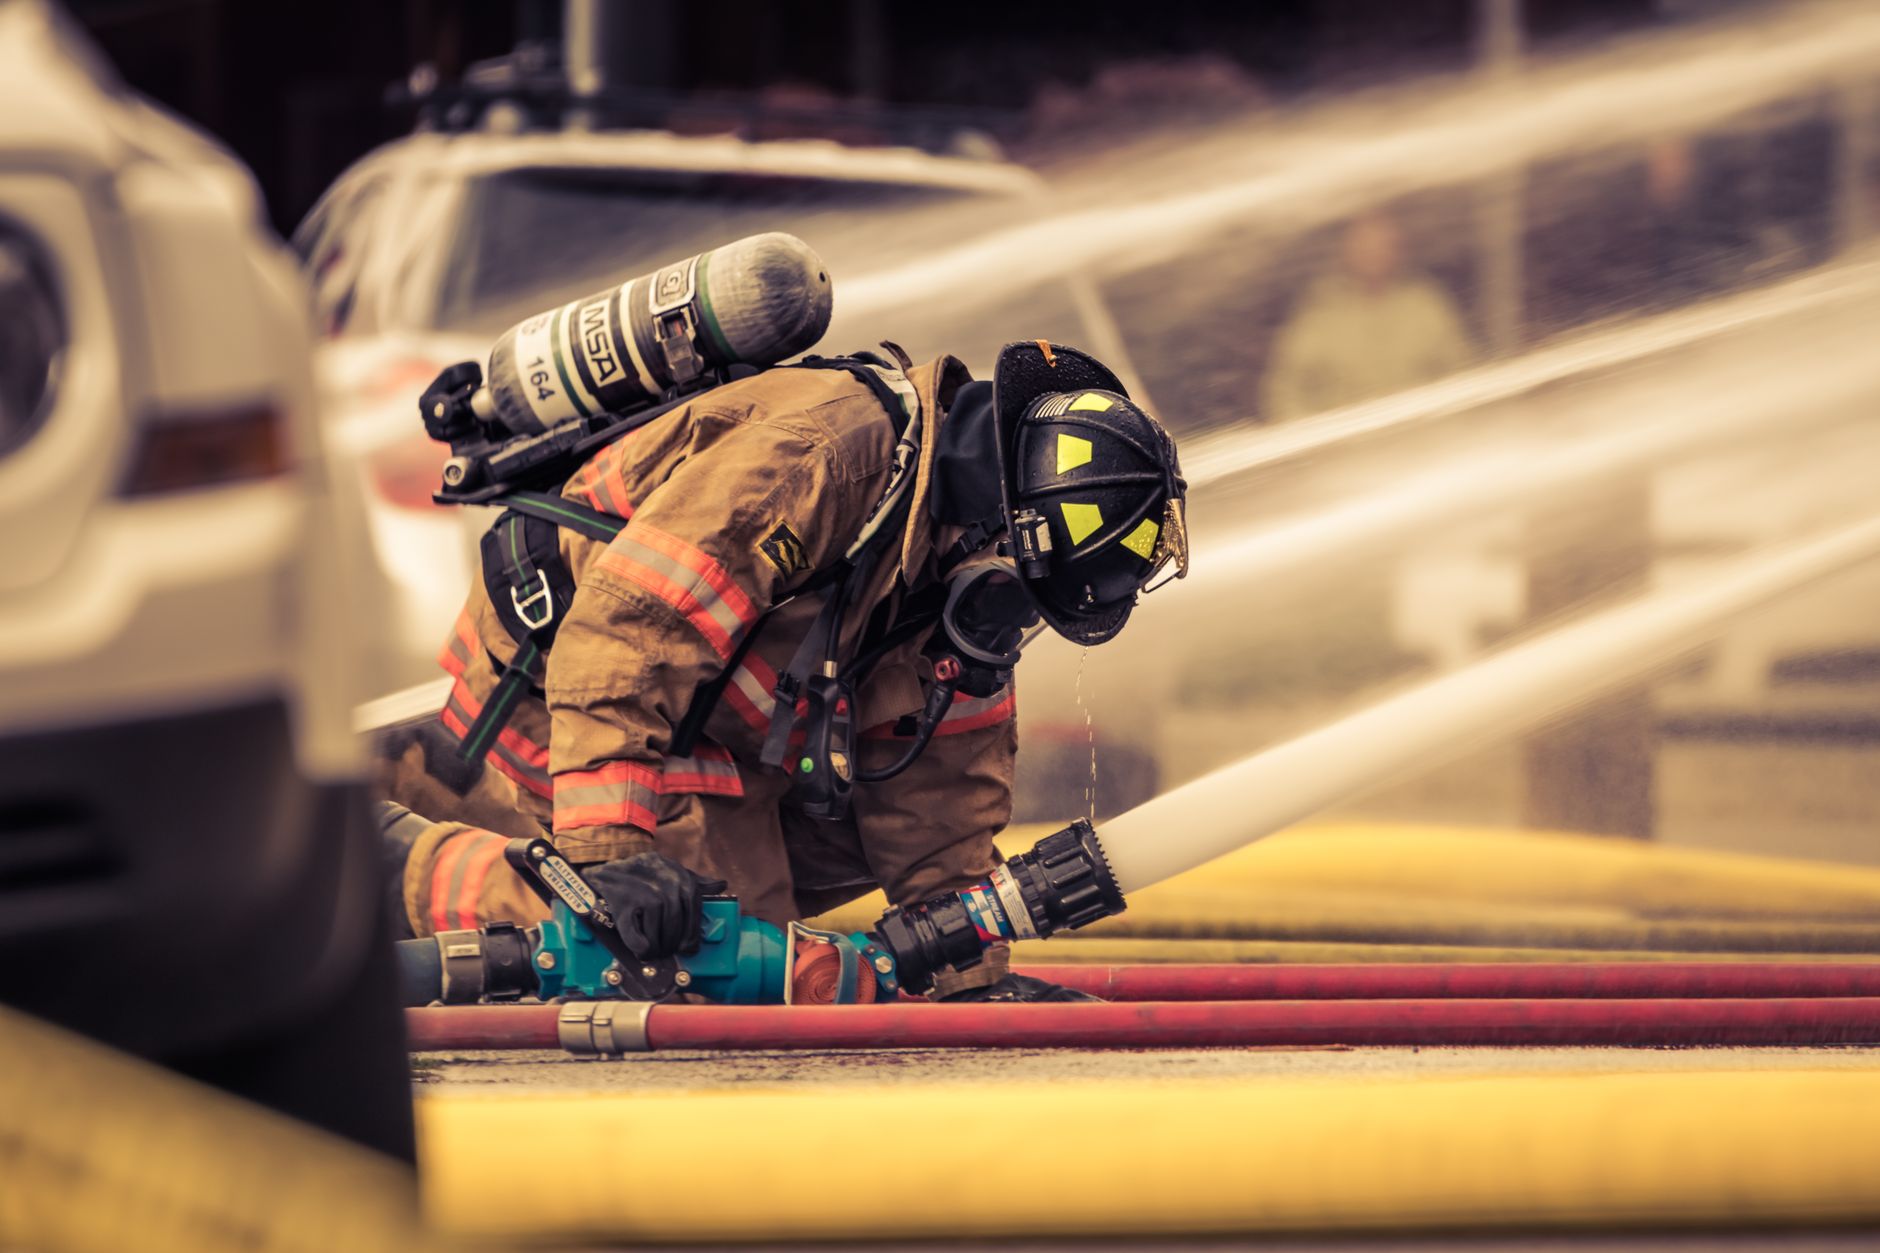
    Retained firefighter in protective kit during training, representing the recruitment pressures at the heart of the retained firefighters crisis
    Photo by Kevin Bidwell on Pexels

    In Scotland, His Majesty’s Fire Service Inspectorate Scotland has flagged concerns about on-call availability repeatedly since 2021. The Scottish Fire and Rescue Service has stations in the Highlands where daytime crew availability falls below the minimum safe threshold several days each month. The service is aware of this. The Scottish Government is aware of this. The response, so far, has been a series of working groups and consultation documents that have produced very little of practical consequence.

    Rural communities have not sat passively through this. Across England, Scotland and Wales, volunteer-led efforts to raise local awareness and keep fire stations visible in community life have proliferated. Parish councils hold fundraising nights. Local businesses sponsor open days. Christmas events, charity auctions, and community fairs serve the double purpose of raising money and reminding residents that the station up the road relies on their neighbours. I’ve seen some inventive approaches to building this kind of local visibility. In one Derbyshire village, the local fire station partnered with a community Christmas event where organisers could see their range for the sleigh run, and ticket sales went directly towards equipment the brigade’s central budget wouldn’t cover. The ingenuity is real. The fact that ingenuity is necessary at all is the damning part.

    The recruitment pipeline that doesn’t exist

    Ask any senior officer in a predominantly rural fire service where the next generation of retained firefighters is coming from, and there is a pause before the answer. Recruitment has never been systematically funded at national level. There is no equivalent of the NHS’s long-term workforce plan, no cross-government strategy that takes seriously the interaction between planning policy, employment law, housing, and fire cover. Whitehall treats the retained firefighters crisis as a matter for individual fire and rescue authorities to manage locally. Individual fire and rescue authorities treat it as a funding problem that only Whitehall can fix. The gap between those two positions is where rural safety goes to die.

    The Fire Brigades Union, which does represent some retained members despite the complexity of their employment status, published a damning briefing in late 2025 arguing that the on-call model itself needs redesign. Their core argument is that asking people to be available for emergency calls whilst holding down a separate job made a kind of sense in an era of stable employment and tight-knit rural communities. In 2026, those preconditions have largely dissolved. The model has not adapted.

    This connects, in ways that are rarely acknowledged, to broader structural shifts in British working life. The hollowing out of middle management and the casualisation of employment across sectors have removed precisely the kind of stable, locally-rooted, employer-supported job that historically produced retained firefighters. You cannot be on-call if your employer changes fortnightly.

    The geography of risk

    What makes the retained firefighters crisis particularly acute is that rural areas face fire risks that are, in several respects, more severe than urban ones. Response times are longer by definition. Properties are more dispersed. Agricultural fires, wildfires, and flooding-related incidents have all increased as the climate has shifted. The number of wildfire incidents recorded in England has risen markedly in the last four years, particularly in moorland areas across Yorkshire, Dartmoor, and the Welsh uplands. These are exactly the communities where retained coverage is thinnest.

    There is also a social dimension that the statistics struggle to capture. In a rural village, the fire station is part of community infrastructure in a way that a city station is not. Its volunteers are your neighbours. When those neighbours stop showing up, it is not only the fire cover that goes; something in the social connective tissue of the place frays too. The pattern of rural public service closure has become familiar enough that communities have learnt to mourn quietly and adapt pragmatically. That adaptation has limits.

    What a credible response would require

    I am not given to listing solutions in a way that flatters the difficulty of the problem, but the basic requirements here are not obscure. A meaningful uplift in the retaining fee, tied to inflation and reviewed regularly. National guidance to employers, backed by statutory weight, requiring them to accommodate on-call duties. A cross-departmental strategy that links housing and planning decisions to emergency service coverage. Targeted recruitment campaigns, funded centrally, in areas where availability has dropped below safe thresholds.

    None of this is happening. The communities affected are, by definition, diffuse and politically underweighted. Rural England, Scotland and Wales do not have the concentrated electoral arithmetic that drives urgent government action. And so the stations sit ready, the appliances wait, and the people who were meant to crew them find themselves unable, legally or practically, to keep doing it. That is the retained firefighters crisis in plain terms. The fire is already spreading.

    For those interested in how Britain’s informal civic workforce is being eroded across multiple domains simultaneously, the parallels with the unpaid carer crisis are uncomfortably close. In both cases, the state has quietly come to depend on voluntary effort it has done nothing to protect.
  • Britain’s Pub Closures Are Accelerating, and the Reasons Go Far Deeper Than the Cost of a Pint

    Britain’s Pub Closures Are Accelerating, and the Reasons Go Far Deeper Than the Cost of a Pint

    The numbers are grim, and they have been for some time. But something has shifted in the past eighteen months. Pub closures in the UK are no longer a slow, melancholy bleed, they have become a haemorrhage. According to the British Beer and Pub Association, Britain is losing pubs at a rate that outstrips anything seen since the 2008 financial crisis, with hundreds closing permanently each quarter. The Campaign for Real Ale (CAMRA) estimates that by mid-2026, more than 50,000 pubs have shuttered their doors since the early 1980s peak. What was once framed as a lifestyle shift, a gentle decline in communal drinking, now looks like something considerably more structural and considerably more alarming.

    I’ve spent time looking at the data behind pub closures UK 2026 presents, and what strikes me is how many separate crises have converged at once. This isn’t one problem. It’s five or six, arriving simultaneously and reinforcing each other in ways that individual interventions can’t easily unpick.

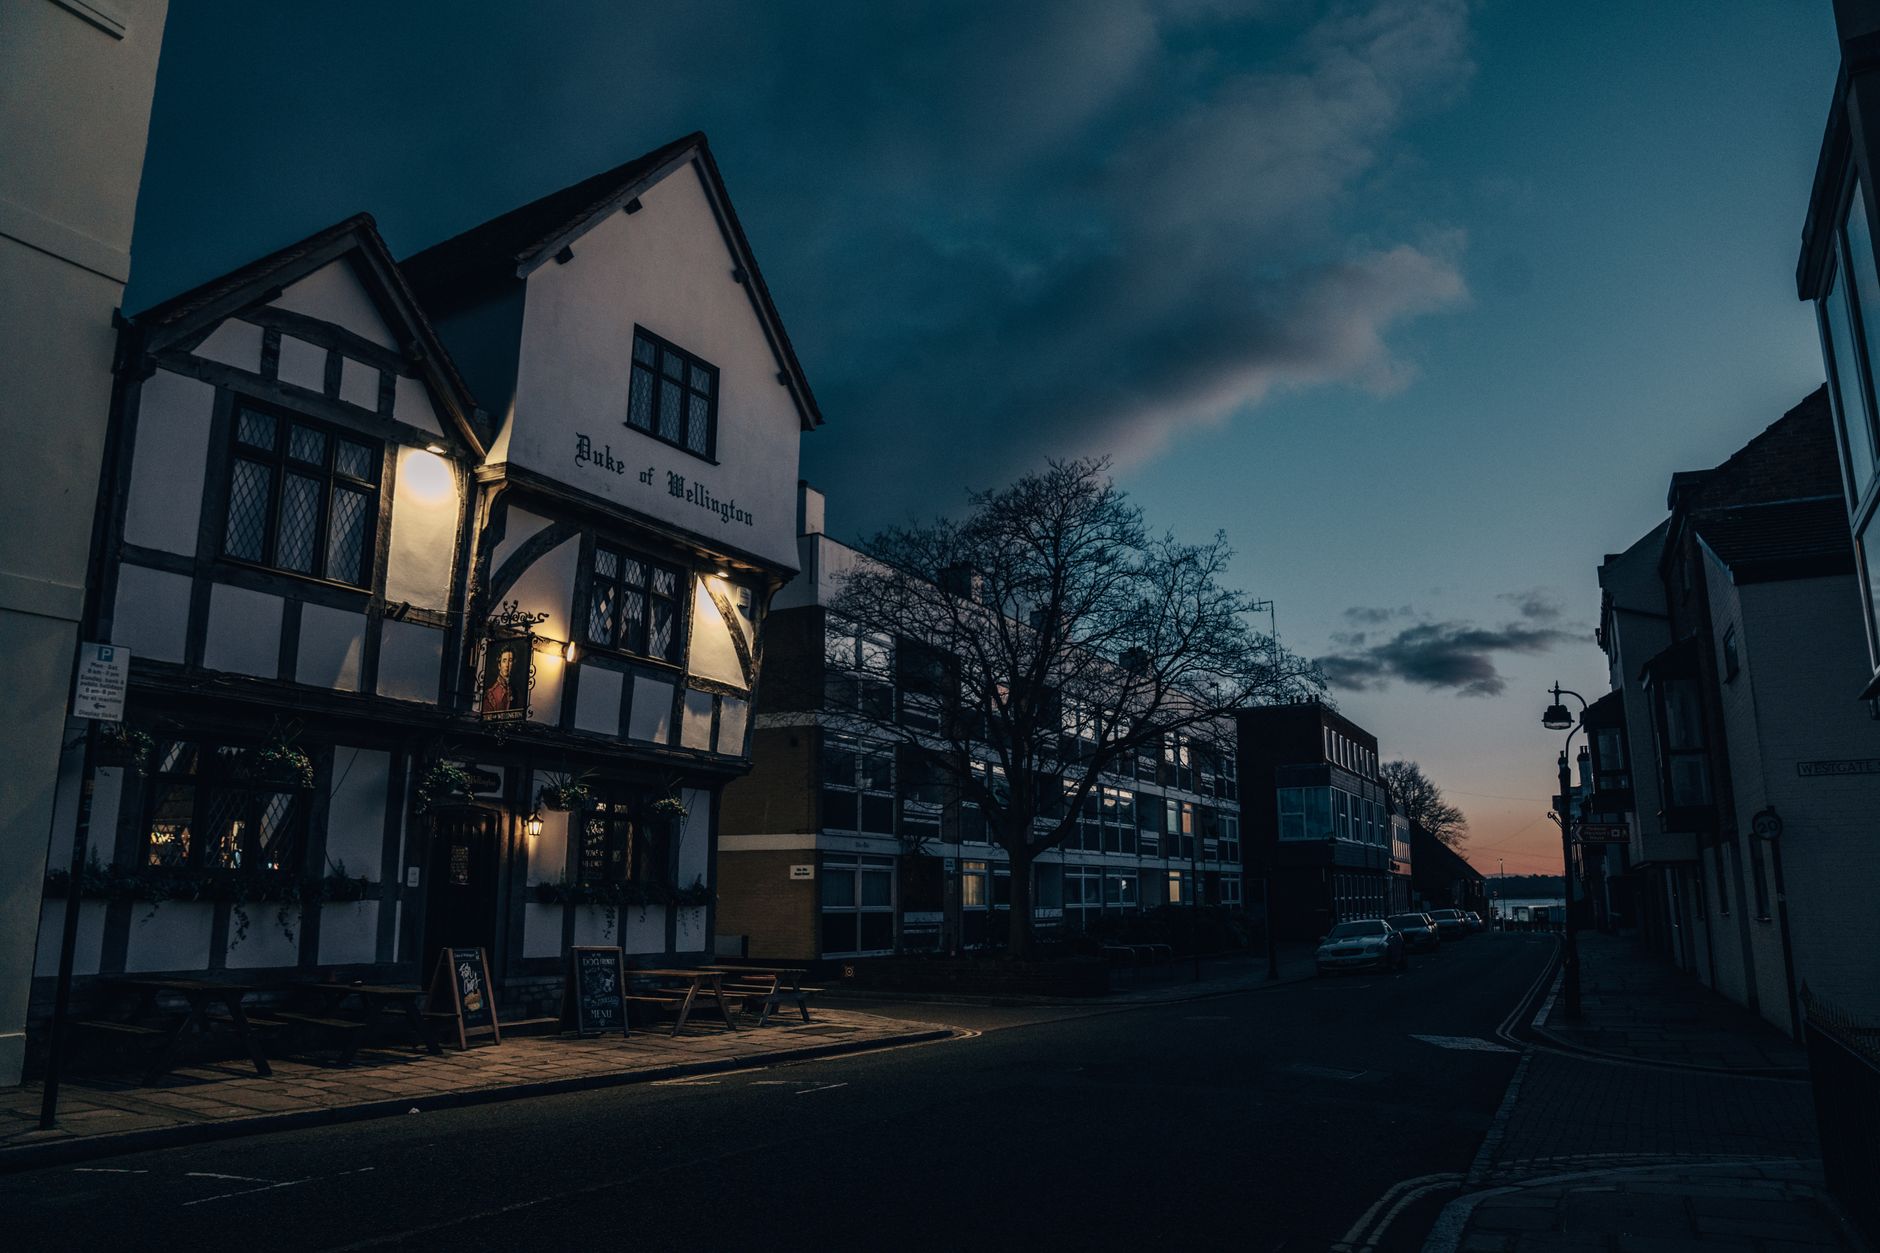
    Traditional English pub exterior on a residential street, relevant to pub closures UK 2026
    Photo by GMB VISUALS on Pexels

    Business rates: the tax that refuses to bend

    Start with business rates, because they remain the single most cited grievance among pub landlords. Unlike retail, which benefited from a string of temporary reliefs during the pandemic years and beyond, wet-led pubs, those that derive their income primarily from alcohol sales rather than food, have received comparatively little structural relief. The current business rates system is based on rateable values that, for many urban pubs, were set against pre-pandemic footfall and now bear no relation to trading reality.

    The British Beer and Pub Association has repeatedly called for a fundamental restructuring of how pubs are assessed, arguing that a pub turning over £400,000 a year in a market town pays proportionally far more in rates than an Amazon warehouse turning over fifty times that. The 2023 revaluation brought some relief for lower-value properties, but it pushed up assessments for pubs in areas where property values had risen, including swathes of London, Bristol and Edinburgh, just as those pubs were trying to recover from years of closure-enforced debt.

    Energy costs are quietly finishing the job

    If business rates are the structural wound, energy costs are the infection that prevents it healing. A typical community pub uses somewhere between 25,000 and 60,000 kilowatt hours of electricity a year, plus substantial gas for cooking and heating. When the energy price cap for commercial customers was effectively removed and wholesale prices spiked, many landlords found themselves facing energy bills three or four times their pre-2022 level.

    Ofgem’s standing charge structure, which I’ve written about before in the context of household bills, hits commercial premises even harder, because the fixed daily charge scales poorly with intermittent use. A pub that opens four evenings a week still pays the full standing charge for all seven days. Several landlords I’ve read about in trade press accounts describe the standing charge alone running to thousands of pounds a quarter, before a single pump is pulled.

    The consequence is that survival increasingly depends on food revenue, which in turn requires investment in kitchen equipment, staffing and ingredients that many traditional locals simply cannot afford. The pub that was, for decades, a place you went for a pint and a bag of crisps is being pushed by economics into becoming a restaurant, or closing.

    Changing drinking habits and who bears the cost

    The cultural picture is more complicated than a simple “people are drinking less” narrative, though that element is real. Britain’s relationship with alcohol has been quietly changing for years, and it has accelerated. Younger adults are drinking less than any previous generation on record. According to the Office for National Statistics, the proportion of 16 to 24 year olds who don’t drink at all rose from around 18% in 2005 to nearly 26% in 2023. That cohort is now in its late twenties and thirties, and many have simply never formed the habit of regular pub attendance.

    The demographic most likely to visit a pub two or three times a week remains the over-45s, a cohort that is ageing out of the pattern. That isn’t doom-saying; it’s arithmetic. And it explains why the closures are hitting certain communities harder than others. Rural areas and post-industrial towns in the North of England, the Welsh valleys and the Scottish lowlands are losing pubs at roughly twice the rate of affluent urban commuter zones. CAMRA’s most recent data shows Yorkshire and the Humber, and the North West, consistently recording the highest closure rates by region. These are places where the pub was genuinely a community anchor, not a lifestyle accessory.

    The home-delivery economy and the supermarket effect

    There’s a third competitor that doesn’t appear in many business rates discussions but deserves serious attention: the sheer convenience of staying home. The explosion in home-delivery food platforms, Deliveroo, Just Eat, Uber Eats, means that the evening a family might once have spent at the local pub’s kitchen is now spent on a sofa with a phone order. This isn’t anyone’s fault, and it isn’t reversible through policy. But it has materially altered the economics of food-led pubs, which now compete with platforms offering the same cuisines at lower perceived cost and zero transport effort.

    Then there is the supermarket effect, long documented but still underappreciated. The price differential between a pint in a pub and a can purchased from a supermarket is now, in many cases, 400% or more. A four-pack of premium lager from a major supermarket costs roughly £5 to £6. The same volume poured in a pub, accounting for glass size, costs £14 to £18 in most English cities. That gap has widened steadily as draught beer costs have risen alongside everything else. For households managing tight budgets, and millions are, the calculus is simple.

    Which pubs are actually surviving, and why

    The picture isn’t uniformly bleak, which makes it all the more instructive. The pubs that are surviving in 2026 tend to share certain characteristics: they own their freehold or hold long, low-rent leases; they have diversified revenue (accommodation, events, community use); and they have invested in energy efficiency measures that meaningfully reduced their utility exposure. Several that have thrived are registered community benefit societies, effectively owned by local residents who voted with their wallets to keep the building open. CAMRA’s Pub of the Year shortlists now read almost entirely as a parade of community-owned or freehold-held venues.

    The tied pub model, where a landlord rents from a pubco and is obliged to buy beer from that pubco at above-market prices, remains a grinding disadvantage for those still within it. The Pubs Code, which gave tied tenants the right to go free-of-tie on fair terms, has been partially effective, but enforcement through the Pubs Code Adjudicator has been slow and contested. The structural problems in the tied model predate the current crisis by decades.

    What would actually make a difference

    CAMRA and the British Beer and Pub Association are aligned on several asks: a permanent lower rate of VAT on draught beer (currently 20%, reduced briefly during the pandemic), a fundamental reform of the business rates system that genuinely reflects trading conditions rather than property values, and an extension of community asset protections that make it harder to convert a pub into flats without meaningful local consultation.

    The government’s current position, as outlined in responses to the House of Commons Business and Trade Committee inquiry into the hospitality sector, is supportive in language and modest in action. A 1p reduction in beer duty was announced for 2026. It is welcome, and it is not enough.

    My reading of the figures is this: the pub closures UK 2026 is recording are not primarily the consequence of any single policy failure. They are the compound result of a tax system designed for a different century, an energy market that penalises small commercial users, a consumer economy that increasingly rewards convenience over community, and a generational shift in drinking culture that no amount of nostalgia will reverse. Some of these forces can be blunted by government. Others cannot. What’s clear is that without structural intervention on business rates and energy, the rate of loss will continue to accelerate, and the communities that can least afford to lose a local will be the ones that do.

    Frequently Asked Questions

    How many pubs have closed in the UK in 2026?

    CAMRA estimates that the total number of pubs lost since the 1980s peak has now passed 50,000. The British Beer and Pub Association reports that closures in 2025 and into 2026 are running at rates comparable to the post-2008 recession period, with hundreds closing each quarter. The precise in-year figure for 2026 will be confirmed in the BBPA’s annual statistical handbook.

    Why are pub closures accelerating now specifically?

    Several structural pressures converged at once: business rates assessments that don’t reflect post-pandemic trading, commercial energy bills that remain significantly above pre-2022 levels, and a sustained shift in younger consumers’ drinking habits. The tied pub model also continues to burden many landlords with above-market beer costs. No single cause is solely responsible, but the combination is proving lethal for marginal venues.

    Which areas of the UK are losing the most pubs?

    CAMRA data consistently identifies Yorkshire and the Humber, and the North West of England, as the regions with the highest closure rates. Rural communities and post-industrial towns are disproportionately affected, partly because the pub often served as a primary community space and partly because those areas have fewer alternative revenue streams such as tourism or affluent commuter trade.

    Does the business rates system treat pubs unfairly compared to other businesses?

    The British Beer and Pub Association argues strongly that it does. Wet-led pubs pay rates assessed on rateable values that bear little relation to current turnover, and they receive fewer reliefs than retail or office-based businesses. The 2023 revaluation actually increased assessments for pubs in areas where property values had risen, compounding the problem at a time when many landlords were still carrying pandemic-era debt.

    What can local communities do to save a pub at risk of closure?

    Communities can apply to have a pub listed as an Asset of Community Value under the Localism Act 2011, which gives local groups a six-month right to bid when it comes up for sale. Several pubs have been saved through community buyouts structured as cooperative or community benefit societies. CAMRA’s website provides detailed guidance on the process, and Locality (the community enterprise network) offers practical support for groups pursuing this route.

  • The Hollowing Out of Britain’s Middle Management: Why a Whole Layer of the Workforce Is Disappearing

    The Hollowing Out of Britain’s Middle Management: Why a Whole Layer of the Workforce Is Disappearing

    Something quiet and structural is happening inside British organisations, and most people affected by it only realise once a redundancy notice lands on their desk. The layer of the workforce that once translated boardroom strategy into front-line action, the team leaders, departmental heads, regional managers and programme coordinators who kept organisations coherent, is shrinking. Fast. Middle management decline in the UK is not a new conversation, but the pace at which it is now accelerating, driven by a confluence of AI tools, post-pandemic cost pressure and a genuine philosophical shift among executives about how companies should be structured, means it deserves serious attention rather than another round of corporate platitudes about “empowering the frontline”.

    Empty corporate meeting room representing middle management decline in the UK
    Photo by Jan van der Wolf on Pexels

    The ONS Labour Force Survey has tracked a steady reduction in “professional and associate professional” occupations in the private sector since 2022, and what those numbers mask is the specific hollowing-out of the managerial middle. Deloitte’s 2025 UK Workforce Survey found that 43 per cent of large British employers had reduced managerial headcount in the previous eighteen months, with the majority citing a combination of automation, flattened hierarchies and a desire to cut overhead costs as the primary rationale. That is not a trend. That is a structural dismantling.

    What is actually driving this?

    Three forces are converging at once, and it is their combination rather than any single factor that makes this moment different from previous waves of corporate delayering in the 1990s or post-financial-crisis era.

    First, AI tools have taken on an enormous amount of what middle managers actually spent their days doing. Progress reporting, rota scheduling, performance data aggregation, meeting summaries, project status updates: software now handles all of it faster and at a fraction of the cost of a £60,000-a-year regional manager. Tools like Microsoft Copilot, integrated across enterprise Microsoft 365 environments, have made it technically feasible for a single senior leader to oversee a team of thirty or forty people who would previously have needed two or three layers of management beneath them. Firms are not blind to this. They are acting on it.

    Second, the pandemic fundamentally changed how leaders think about what organisations need. Remote and hybrid working stripped away a category of management activity that nobody quite wanted to name: presence management. A significant portion of middle management’s value in many traditional British firms was, frankly, making sure people turned up and looked busy. Once that function became impossible to perform, executives started asking what their middle tier was actually for, and some did not like the answer.

    Third, cost. The UK economic environment since 2022 has been brutal for business margins. Rising employer National Insurance contributions (the April 2025 increase to 15 per cent from 13.8 per cent was a meaningful shock to payroll costs), energy costs, and persistent inflation have made every line of the headcount plan a target for scrutiny. Middle management salaries, clustering between £40,000 and £85,000, represent an obvious and significant saving per head.

    Who is being cut, and in which sectors?

    The pattern is most pronounced in financial services, retail, media and professional services. HSBC, which announced the elimination of several hundred middle-tier roles in its UK operations in late 2024, is the most high-profile example, but it is hardly alone. The retail sector has seen waves of regional and area manager redundancies as head offices argue that store data is now directly accessible at board level. At one major British supermarket chain (not publicly named in its internal restructuring documents, though widely reported in the trade press), the ratio of managers to frontline workers shifted from 1:8 to 1:16 between 2022 and 2025.

    Professional at desk reflecting the pressures behind middle management decline in UK workplaces
    Photo by cottonbro studio on Pexels

    Professional services firms have also started cutting what they’re calling “coordination overhead”, essentially anyone whose job was to sit between client-facing staff and senior partners. Marketing agencies, accountancy practices, and management consultancies have all trimmed their associate director and senior manager cohorts. I’ve spoken to people in their early forties who spent fifteen years building a career pathway that simply no longer exists in the form they trained for.

    The career progression problem nobody is solving

    Here is the thing that concerns me most about middle management decline in the UK: the ladder is disappearing, but nobody is building a replacement. Organisations have cheerfully talked about “horizontal career pathways” and “specialist tracks”, but the reality for most British workers is that the traditional promotion structure gave people both aspiration and financial progression. Remove the rungs and you do not get a more empowered workforce; you get a ceiling that arrives ten years earlier in a career than it used to.

    This connects to a broader anxiety about professional identity in Britain. The brain drain we are already seeing among skilled graduates choosing to build careers elsewhere will only worsen if the domestic career escalator stalls for people in their thirties and forties. The professionals who would previously have spent a decade climbing through management roles are now being told to “own their own development” at exactly the moment the organisation has removed the positions they were developing towards.

    There is also a knowledge retention problem. Middle managers are not merely bureaucratic overhead; in most organisations they are the institutional memory. They know which clients are difficult, which processes have workarounds, which junior team members need support. When that layer goes, the knowledge goes with it, and the assumption that senior leaders can absorb it all whilst simultaneously doing more with fewer people around them is, in my reading, optimistic to the point of fantasy.

    What the affected professionals are actually doing

    I have noticed a distinct pattern in how displaced middle managers are responding. Many are pivoting towards fractional or interim work, offering their sector expertise to multiple smaller businesses rather than a single employer. Others are moving into consultancy, setting up as independent advisers in areas where their sector knowledge still commands a premium. The irony is that some of them are then hired back by the very organisations that made them redundant, on day-rate contracts that cost considerably more per hour than their previous salaries, because the institutional knowledge problem becomes obvious within months.

    For those looking to rebuild their professional profile independently, digital visibility matters more than it ever did. Everything from a polished LinkedIn presence to a proper online portfolio is now table stakes. Firms like WDM have seen a surge in sole traders and newly independent consultants investing in their own digital presence as the employed middle management route closes off for them.

    The broader organisational culture implications are also worth naming. Flatter organisations can work brilliantly when they are genuinely well-designed and when senior leaders actually have the bandwidth to operate across wider spans of control. But many British firms have not redesigned their organisations at all; they have simply removed people and expected the remaining structure to absorb the gap. The result is senior leaders stretched beyond capacity and junior employees with nobody to mentor them through the early stages of their careers. The burnout crisis already visible at senior leadership level is in part a consequence of this dynamic.

    Can this trend reverse?

    Some economists argue that a degree of delayering is genuinely healthy. Bureaucratic bloat is real, and there were certainly organisations carrying management layers that added limited value. But the current pace of middle management decline in the UK risks overcorrecting badly, and the organisations that survive it best will be the ones that were deliberate and strategic about which management functions genuinely could be automated and which ones required human judgement, relationship management and cultural continuity.

    The ageing profile of Britain’s workforce adds another dimension. Many of those caught in this middle management squeeze are in their mid-forties to mid-fifties, close enough to retirement that retraining feels daunting but too far away to step back from work. The human cost of this structural shift is not yet visible in aggregate statistics, but it will be.

    The organisations that will look back on this period with satisfaction are those that treated the question of management structure as a genuine design challenge. The ones that will struggle are those that treated it as a headcount reduction exercise with a flattering narrative attached. Britain’s corporate culture has a long history of dressing up cost-cutting as strategy. This time, the consequences will be harder to paper over.

    Frequently Asked Questions

    Why is middle management declining in UK companies?

    A combination of AI tools taking on coordination and reporting tasks, post-pandemic shifts in how organisations operate, and significant cost pressure on payroll (especially following April 2025 National Insurance rises) has led many UK firms to cut middle management tiers. The rationale is that flatter structures are cheaper and that technology can now handle much of the administrative work those roles involved.

    Which industries are cutting the most middle managers in the UK?

    Financial services, retail, media and professional services have seen the most significant reductions. HSBC, major supermarket chains and various marketing and consultancy firms have all reduced their managerial middle tier noticeably since 2022. The pattern is most acute in sectors where digital tools can aggregate performance data directly at senior level.

    What happens to career progression when middle management disappears?

    The traditional promotion ladder shortens considerably, meaning professionals in their thirties and forties hit a ceiling much earlier than previous generations did. Many organisations talk about horizontal career pathways and specialist tracks as alternatives, but these rarely match the financial progression that management promotion used to provide.

    What are displaced middle managers doing after redundancy?

    Many are moving into fractional or interim roles, offering their expertise across multiple businesses rather than one employer. Others are setting up as independent consultants. A significant number report being re-engaged by former employers on day-rate contracts, often at higher effective cost, once the institutional knowledge gap becomes apparent.

    Is the decline in middle management bad for organisations long-term?

    Where the delayering is deliberate and well-designed, it can improve responsiveness and reduce bureaucracy. Where organisations have simply removed people without redesigning workflows, the result tends to be overstretched senior leaders, under-supported junior staff and a loss of institutional knowledge that proves costly within one to two years.