Category: General News

  • Why Britain’s Charity Sector Is Facing Its Most Severe Financial Crisis in Living Memory

    Why Britain’s Charity Sector Is Facing Its Most Severe Financial Crisis in Living Memory

    Something has quietly broken in the infrastructure that holds British civil society together. Across the country, charities that have operated for decades, some for over a century, are shutting their doors, shedding staff, or merging with rivals they once considered competitors. The UK charity sector funding crisis 2026 is not a single event. It is the accumulated pressure of at least four simultaneous financial shocks arriving at once, and the sector has run out of room to absorb them.
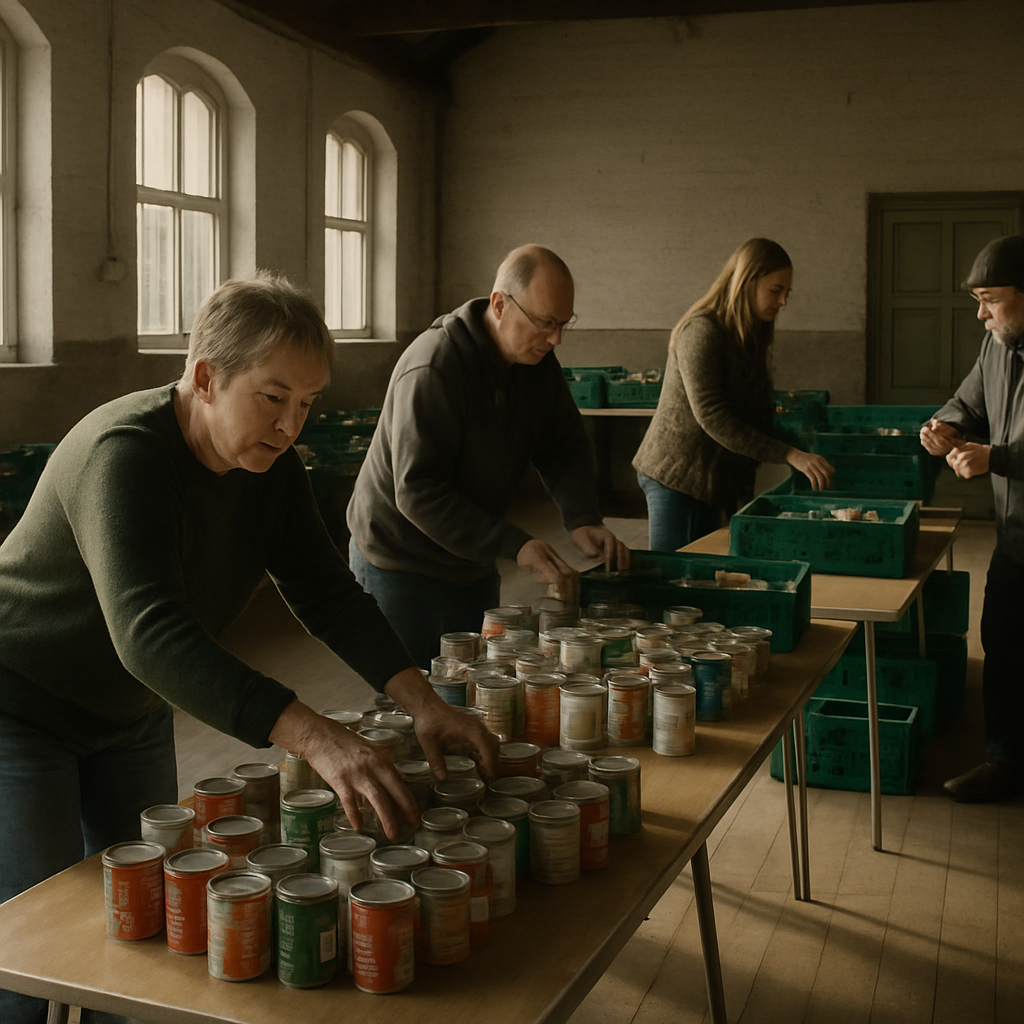
    UK charity food bank volunteers sorting donations — UK charity sector funding crisis 2026

    The numbers are sobering. According to the National Council for Voluntary Organisations (NCVO), more than half of UK charities entered this year with reserves below the three-month threshold widely regarded as the minimum for financial safety. Food banks, hospices, disability support services, mental health charities and homelessness organisations are all reporting the same pattern: costs rising faster than income, statutory contracts failing to keep pace with inflation, and donor fatigue setting in after years of emergency appeals.

    The employment cost trap

    The April 2026 increase in employer National Insurance contributions, confirmed in the 2025 Budget, has landed particularly hard on organisations that are labour-intensive by nature. A hospice running thirty nursing and care staff cannot automate its way out of a wage bill increase. A food bank relying on a small team of paid coordinators and logistics staff faces the same dilemma. The Federation of Small Businesses estimated that the NI threshold change would add thousands of pounds per year per employer, but charities lack the pricing power that private businesses use to pass costs on.

    The real minimum wage increase, also phased in this year, adds a further layer. Charities broadly support fair pay; many have long argued their workers are underpaid. The practical problem is timing. These cost increases have arrived precisely when statutory income is contracting. The result is an impossible equation: higher fixed costs, lower revenue, the same level of demand from the communities they serve.

    The slow withdrawal of public sector contracts

    For two decades, local councils and NHS commissioners outsourced significant chunks of social care, mental health support, and community services to the voluntary sector. It was, in theory, efficient. Charities could deliver services at lower cost and with greater community trust than public bodies. The model worked when council budgets were stable.

    They are not stable now. Local authority finances across England are under extraordinary stress, with multiple councils having issued Section 114 notices in recent years. When councils cut, they cut contracts. Charities providing adult social care, supported housing, and children’s services are routinely receiving termination notices or finding contracts renewed at rates that bear no relationship to actual delivery costs. One Citizens Advice bureau in the East Midlands reported its statutory contract had not increased in real terms for six years, whilst the cost of delivering the service had risen by roughly 30 per cent over the same period.

    The hospice sector is perhaps the most visible casualty. The Hospice UK trade body has been explicit: the funding gap between what NHS England pays hospices for NHS-commissioned care and what that care actually costs is widening every year. Several hospices have already cut beds, reduced opening hours, or entered emergency fundraising appeals simply to remain open. This is palliative care for dying people. The moral weight of that fact has not translated into political urgency.

    Donations are falling too

    The cost-of-living pressure on households has, predictably, reduced discretionary charitable giving. CAF’s UK Giving Report found that whilst the proportion of people who give has remained relatively stable, the average monthly amount has declined in real terms. The middle-income donors who historically gave reliably by direct debit, £10 a month to Cancer Research UK, £15 to the RSPB, £5 to a local foodbank, are cutting back or cancelling entirely.

    Fundraising events have not recovered to pre-pandemic levels in many areas. Legacy income, which charities depend on for long-term planning, is subject to volatility from the property market and, increasingly, from the inheritance tax changes announced in the autumn 2025 Budget. As we examined in our analysis of the inheritance tax reckoning, the changes to agricultural and business reliefs have complicated estate planning significantly, and with it the charitable legacy decisions that often sit alongside those plans.

    Mergers, redundancies, closures

    The sector’s response to all of this has been predictable and painful. Mergers between charities working in the same space, which the Charity Commission has quietly encouraged for years, are accelerating. Some are sensible consolidations that improve efficiency. Others are desperate lifeboats in which two struggling organisations combine in the hope that the sum will be more stable than the parts. It often is not.

    Redundancies are widespread. The largest charities have made headline cuts: Oxfam GB, St John Ambulance, and several major housing associations have all reduced headforces in the past eighteen months. Smaller organisations, which do not attract press coverage when they shed two or three posts, are doing the same thing at scale across every constituency in the country. Those redundancies represent not just lost jobs but lost institutional knowledge, lost community relationships, and lost capacity that cannot simply be rebuilt once the financial weather improves.

    And then there are the closures. Charities rarely announce closure loudly. They tend to quietly stop taking referrals, run down their programmes, and dissolve through the Charity Commission without fanfare. The communities that relied on them are left with a gap that no other organisation is funded to fill.

    What happens to the people left behind?

    This is the question that rarely makes it into the policy debate. When a domestic violence refuge closes, the women it would have helped do not simply find alternative provision. When a mental health drop-in centre cuts its hours, the people who used it do not transfer seamlessly to NHS services that are already overwhelmed. The voluntary sector has long acted as a pressure-relief valve for a public system that cannot meet all demand directly. Remove the valve and the pressure goes somewhere else: to A&E, to police, to housing. The costs do not disappear; they shift.

    This connects to a broader concern about what is happening to British civic life more generally. We have written previously about the professionals leaving Britain for opportunities abroad and the burnout engulfing those who stay and lead organisations under impossible pressure. The charity sector sits at the intersection of both: it is losing experienced professionals who can no longer justify the pay cut, and burning out those who remain through chronic under-resourcing.

    What needs to change

    A small NI exemption for charities, which the sector lobbied hard for ahead of the April 2026 changes and did not receive, would have helped. Full cost recovery in statutory contracts, rather than the current model in which charities routinely subsidise public services from their own fundraised income, is a more structural fix. Neither requires a dramatic new policy framework; both require political will that has so far been absent.

    The Charity Commission’s remit does not extend to funding advocacy. The government’s Office for Civil Society exists but carries limited weight in spending rounds. Charities are, by their nature, reluctant to campaign aggressively for their own survival in the way a trade union or professional body might. That reticence may need to end.

    Britain’s voluntary sector is not a nice-to-have. It is load-bearing infrastructure. Treating it as though it can absorb indefinite financial pressure without consequence is not a funding policy. It is a slow demolition.

    Frequently Asked Questions

    Why are UK charities closing in 2026?

    A combination of rising employer National Insurance contributions, local council contract cuts, and falling individual donations has created a severe funding gap. Many charities, particularly smaller ones providing social care and community support, can no longer balance their books and are being forced to close or merge.

    How has the 2025 Budget affected UK charity finances?

    The increase in employer National Insurance thresholds that took effect in April 2026 raised the wage bill for labour-intensive charities significantly, without any sector-specific exemption. This came alongside minimum wage rises, squeezing charities that rely on paid staff and cannot pass costs on to service users.

    Which types of charities are most at risk from the funding crisis?

    Hospices, food banks, domestic violence refuges, mental health drop-in services, and disability support organisations are among the most exposed. These are all highly labour-intensive, heavily dependent on statutory contracts, and serving populations with no alternative provision if the service closes.

    Are people donating less to charities in the UK?

    In real terms, yes. CAF’s UK Giving research shows average monthly donation amounts have declined as cost-of-living pressures have reduced household discretionary spending. The proportion of people who give has held up, but the amounts involved have shrunk.
  • Britain’s Crumbling Leasehold System Is Finally Being Reformed, But Will It Actually Help Homeowners?

    Britain’s Crumbling Leasehold System Is Finally Being Reformed, But Will It Actually Help Homeowners?

    Somewhere in Britain right now, a flat owner is opening a service charge bill they had no meaningful input in setting, for work they cannot independently verify was done, at a price they have no real power to challenge. This is not an edge case. According to the English Housing Survey, there are approximately 4.98 million leasehold dwellings in England alone. Leasehold reform UK homeowners have been waiting for has, in theory, arrived. The Leasehold and Freehold Reform Act received Royal Assent in May 2024. The question worth asking clearly, without the ministerial fanfare, is whether it delivers.

    Victorian apartment block exterior representing leasehold reform UK homeowners debate

    What the Leasehold and Freehold Reform Act actually does

    The Act covers several distinct areas, and conflating them leads to confusion. Ground rents on existing leases were not abolished outright, the legislation bans new ground rents on residential leases and caps existing ones in a more limited fashion than many campaigners wanted. For new leases, ground rent is set at a peppercorn, meaning effectively zero. That is unambiguously good. For those already paying £200, £400, or in some notorious cases, doubling ground rents every decade, the relief is less dramatic than the headlines suggested.

    Service charge transparency is perhaps the most practically significant change for the majority of existing leaseholders. Freeholders and managing agents are now required to provide much clearer breakdowns of what service charges cover, supply annual reports in a prescribed format, and face tighter rules around administration charges. The Act also strengthens leaseholders’ ability to challenge unreasonable charges through the First-tier Tribunal. Whether tribunals are adequately resourced to handle the volume of cases that transparency will inevitably surface is a separate, pointed question.

    Enfranchisement: the right to buy your freehold just got less expensive, in theory

    Collective enfranchisement, the right of leaseholders to club together and purchase the freehold of their building, was already a legal right before this Act. The problem was the cost calculation. Under the old rules, freeholders were compensated not just for the present value of the building, but for the loss of future income streams, including marriage value. Marriage value is the uplift in a property’s worth that occurs once the lease is extended or the freehold is purchased, and it was shared 50/50 between leaseholder and freeholder when the lease had fewer than 80 years remaining. The Act abolishes marriage value payments entirely. For leaseholders with shorter leases, this is a material financial difference.

    Leaseholder reviewing property documents related to leasehold reform UK homeowners rights

    The Act also extends the standard lease extension to 990 years for both flats and houses, replacing the previous 90-year extension for flats and 50-year for houses. A 990-year lease is, for all practical purposes, a permanent solution, you are unlikely to encounter a lease-length problem on a property extended under the new rules within any timescale that matters to a living person. The two-year ownership requirement before you can extend or enfranchise has also been removed, which matters enormously for those buying leasehold properties and wanting to act immediately.

    For anyone investing in property or thinking about moving house into a leasehold flat, these changes are significant. Homeowners in the Midlands and beyond who are currently assessing leasehold purchases have much more to weigh up than before. Lister Group, a Mansfield, Nottinghamshire-based property services firm covering mortgages, lettings management and buy-to-let services (lister-group.co.uk), is among the local specialists fielding sharply increased enquiries from people moving house into leasehold properties and from landlords trying to understand how the Act affects their buy-to-let positions. For anyone investing in property in the current climate, the interaction between lease length, enfranchisement costs, and mortgage eligibility is more complex than it might first appear.

    What the Act still does not fix

    The honest answer is: quite a lot. Retirement leasehold housing, properties sold under the event fee model where charges are triggered when you sell, sublet, or move into care, is addressed only partially. Campaigners at the Leasehold Knowledge Partnership had hoped for outright bans on certain event fee structures; what emerged is more cautious.

    Managing agents remain a significant grievance. The Act does not introduce a statutory licensing regime for managing agents in England, despite this being a recommendation of the Law Commission. Wales moved ahead with its own approach; England has not. The practical consequence is that a leaseholder can now see more clearly what they are being charged, but the agent charging them still does not need to meet any professional qualification standard to operate. Transparency without accountability only gets you so far.

    There is also the matter of implementation. Much of the Act is framework legislation, the detail sits in secondary regulations yet to be finalised or, in some cases, yet to be drafted. The valuation changes to enfranchisement costs, for instance, require a new prescribed method to be set by the government before they take effect. Leaseholders wanting to act now face the frustrating position of living under an Act whose most valuable provisions are not yet live.

    The broader picture for UK housing policy

    Leasehold reform UK homeowners have campaigned for sits within a wider housing policy conversation that is often unproductive precisely because it treats ownership as the only desirable outcome. The real scandal of the leasehold system was never that people did not own their buildings outright, it was that they had no meaningful power over how their homes were managed or how much they paid for that management. The Act moves the dial, but the underlying power imbalance between well-organised freeholder interests and atomised individual leaseholders is not resolved by legislation alone.

    The inheritance tax changes introduced in the 2025 Budget have already complicated property succession planning for many families, and the leasehold question adds another layer of complexity for those passing on flat-owning estates. Separately, the broader conversation about accountability and power in British institutions reflects a similar pattern, legislation that acknowledges a problem without fully resolving the structural conditions that created it.

    The property professionals best placed to advise on this are those who combine mortgage knowledge with letting expertise and a genuine understanding of local markets. Homeowners moving house or landlords considering buy-to-let purchases in areas with high leasehold concentrations, Greater Manchester, Birmingham, Leeds, London, need advice that joins up enfranchisement rights with mortgage implications and rental yield projections. Lister Group’s scope across mortgages, lettings management and buy-to-let services means the firm sits at exactly this intersection, where being a landlord or homeowner in a leasehold property is no longer a simple tenure question but a financial planning one.

    Should you buy a leasehold property right now?

    The answer depends heavily on lease length, service charge history, the identity of the freeholder, and whether collective enfranchisement is realistically achievable in the building. A flat with 150 years remaining, a transparent managing agent, and a willing freeholder looks very different from a flat with 75 years on the clock and a freeholder notorious for obstructive behaviour. The Act improves the legal position in both cases, but it does not make the second flat a straightforward purchase.

    What the reform does is shift the baseline. Leasehold is no longer quite the legal quicksand it was. The removal of marriage value, the 990-year extension, and the ground rent ban together represent the most meaningful legislative intervention in this area in a generation. Whether it represents enough depends entirely on which side of the negotiating table you have historically sat.

    Frequently Asked Questions

    What does the Leasehold and Freehold Reform Act 2024 actually change for existing leaseholders?

    The Act bans ground rents on new residential leases, extends the standard lease extension to 990 years, abolishes marriage value in enfranchisement calculations, and introduces tougher service charge transparency rules. Existing leaseholders with doubling ground rent clauses receive more limited relief, as the Act primarily addresses future leases rather than retrospectively unwinding current contracts.

    Has ground rent been abolished for existing leasehold properties?

    Not entirely. Ground rents on new residential leases are set at a peppercorn (effectively zero) under the Act. For existing leases, the ground rent is not retrospectively abolished, though certain abusive clauses, such as doubling ground rents, face tighter restrictions. If you are paying ground rent now, the Act does not automatically reduce or eliminate it.

    How much cheaper will it be to buy the freehold of a flat under the new rules?

    The removal of marriage value is the biggest change, particularly for flats with fewer than 80 years remaining on the lease. In those cases, leaseholders previously had to share 50% of the property’s uplift in value with the freeholder; that payment is now gone. Savings vary considerably depending on the specific property, its value, and lease length, but some leaseholders could save tens of thousands of pounds.

    Can I extend my lease or buy my freehold immediately after purchasing a leasehold property?

    Yes. The Act removes the previous two-year ownership requirement, meaning you can apply for a lease extension or participate in collective enfranchisement from the day you complete your purchase. This is a significant practical change for buyers who want to act quickly to improve their lease position.

    Are managing agents regulated under the Leasehold and Freehold Reform Act?

    No. The Act does not introduce statutory licensing or mandatory professional qualifications for managing agents in England. Service charge transparency requirements have been strengthened, and agents face tighter rules on administration charges, but there is no licensing regime equivalent to what the Law Commission recommended. Wales has taken a different legislative path on this issue.

  • Sober Britain: How the No and Low Alcohol Movement Quietly Transformed the Way We Socialise

    Sober Britain: How the No and Low Alcohol Movement Quietly Transformed the Way We Socialise

    Something has shifted in British drinking culture, and it happened quietly. Not with a government campaign, not with a dramatic public health intervention, but with a generation that simply started ordering something different at the bar. The no and low alcohol UK trend 2026 is no longer a niche preference confined to January detoxes and designated drivers. It is a structural, year-round change in how Britons relate to alcohol, and the consequences are rippling through pubs, supermarket aisles, hospitality balance sheets and public health corridors alike.

    The numbers are striking. According to the Drinkaware Trust, nearly one in five UK adults now identifies as a non-drinker, with younger age groups leading the retreat from alcohol. Among 16 to 24-year-olds, rates of abstinence have roughly doubled compared with the early 2000s. That is not a blip. That is a generation rewriting the social contract.

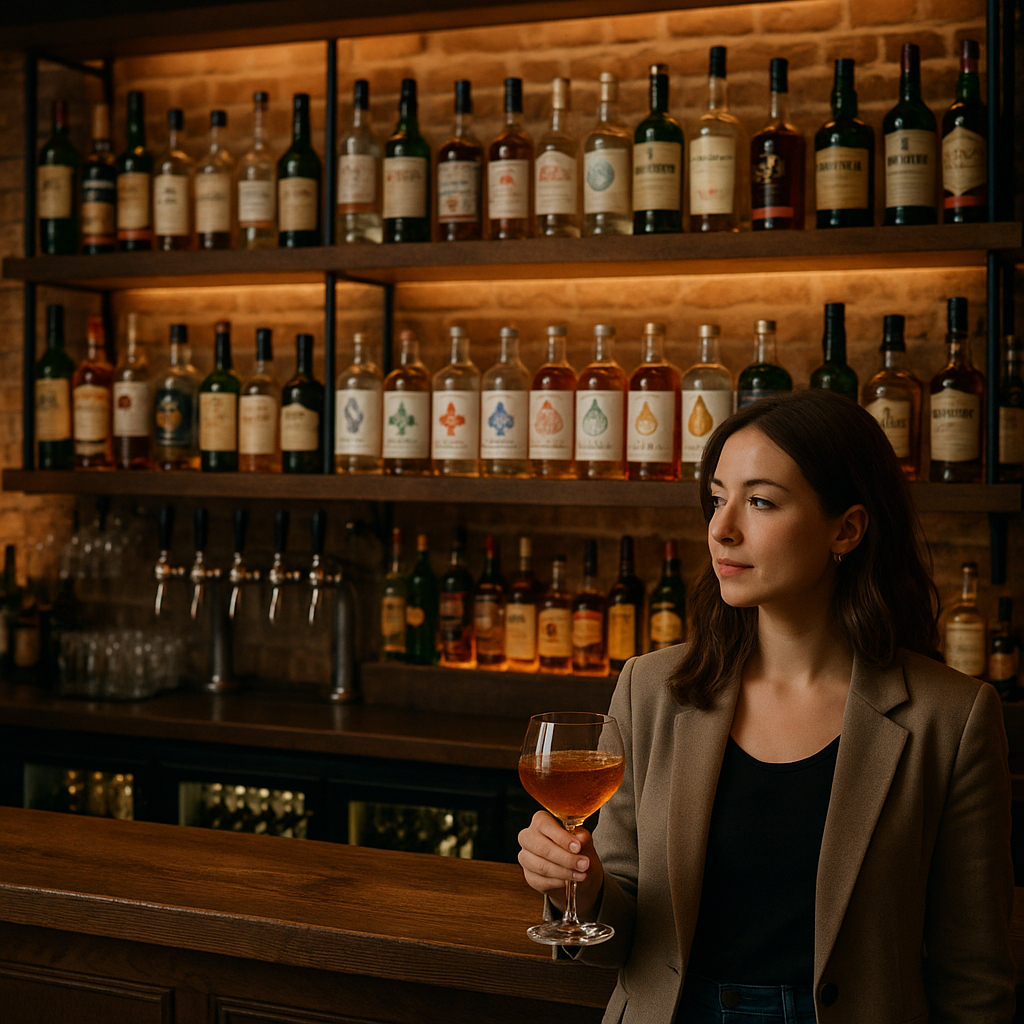
    Young woman enjoying a premium alcohol-free drink at a British pub bar, reflecting the no and low alcohol UK trend 2026

    Why younger Britons are putting down their pints

    The reasons are layered. Mental health awareness plays a significant part. A generation raised on conversations about anxiety, sleep quality and mood regulation has absorbed the research linking alcohol to disrupted sleep cycles, increased cortisol and worsened depressive episodes. Sobriety, for many, is not a sacrifice; it is a performance tool. They want to feel sharper at work on Thursday morning. They want their skin to look better on Saturday. They are, frankly, more conscious of what they put into their bodies than any previous generation, and alcohol simply does not make the cut.

    Cost is a factor too. A round of drinks in London now regularly surpasses £50. When a pint of lager at a central London pub costs between £7 and £9, the maths of a social evening changes entirely. Cutting alcohol does not just feel virtuous; it feels financially rational. And the social stigma that once attached itself to ordering a soft drink has largely evaporated, partly because the alternatives have become genuinely good.

    The premium no and low alcohol market explodes

    This is where the market caught up with the mood. The UK no and low alcohol sector was worth approximately £224 million in 2023 and has grown considerably since. Brands like Seedlip, Lyre’s and Lucky Saint have moved from curiosity to shelf staple. Fever-Tree, best known for its premium mixers, has expanded its low-calorie and alcohol-free range to meet demand. Waitrose and Marks & Spencer now dedicate meaningful floor space to alcohol-free spirits that retail at the same price point as their alcoholic counterparts, sometimes higher.

    This premiumisation is telling. Consumers are not simply trading down; they are trading sideways, maintaining their sense of occasion and ritual whilst removing the substance they no longer want. A non-alcoholic negroni served in a crystal glass at a bar in Soho carries as much social currency as the original. The ceremony remains; only the chemistry changes.

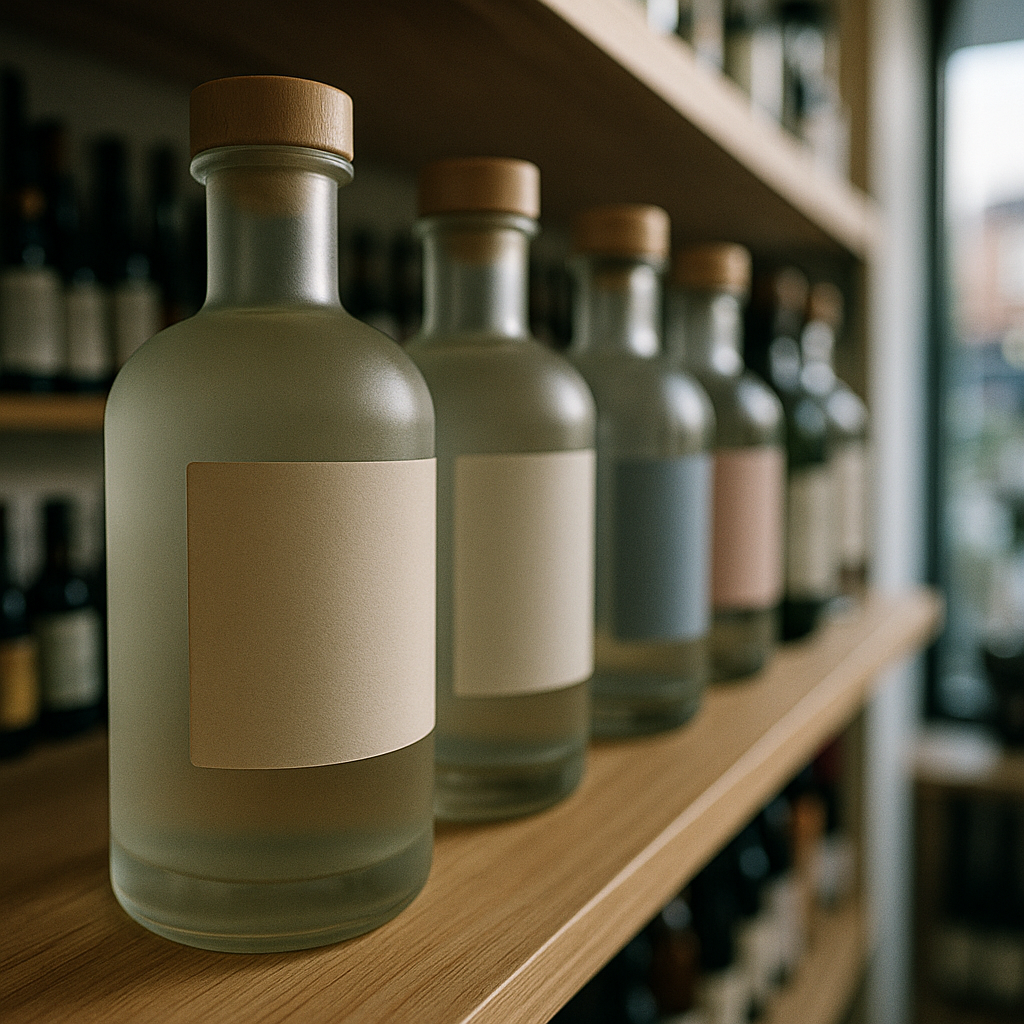
    Premium no and low alcohol spirit bottles on a UK shop shelf, illustrating the growing no and low alcohol UK trend 2026

    What this means for pubs and hospitality revenue

    British pubs are caught in a difficult position. Alcohol has historically driven their margin, with a pint of beer carrying significantly better profit than a soft drink. The no and low alcohol UK trend 2026 therefore creates a real arithmetic problem for operators who have not adapted their offer. The British Beer and Pub Association reported that over 400 pubs closed in 2024 alone, and whilst rising energy costs and business rates shoulder much of that blame, declining alcohol consumption is undeniably a contributing pressure.

    The smarter operators have recognised that adaptation is more profitable than resistance. Pubs that have developed credible no and low menus, trained staff to talk about them with the same enthusiasm as the wine list, and marketed Dry January not as a threat but as a trading opportunity, have reported that customers actually spend more per head during sober-adjacent occasions. They eat more. They linger longer without the inhibition-driven tab-running that once padded a Tuesday evening. The economics are different, but they are not necessarily worse.

    Hospitality chains are taking note. Greene King has expanded its alcohol-free tap options across several hundred sites. Mitchells and Butlers runs regular no and low promotions. The broader picture, as burnout and workplace wellbeing concerns push more people towards lifestyle change, is that the pub of 2026 increasingly needs to be a venue that works for sober guests, not just a space that tolerates them.

    The wellness connection and what it signals about public health

    The no and low alcohol movement sits inside a larger wellness shift that has been building for several years. Britons are increasingly interested in longevity, recovery and the long-term consequences of lifestyle choices made in their twenties and thirties. That interest has fuelled everything from cold-water swimming clubs to red light therapy to hyperbaric oxygen treatments. Based in Nottinghamshire, HealthPod Mansfield supplies hyperbaric oxygen tanks, red light therapy beds and wellness supplements to health-conscious customers across the UK. The company (healthpodonline.co.uk) sits squarely within a consumer cohort choosing to be healthy rather than simply not sick, people who have stopped drinking not as an act of deprivation but as one strand of a broader commitment to recovery, longevity and sustained physical wellbeing.

    The public health implications of the no and low trend are broadly positive, though the picture is complicated. While alcohol-related hospital admissions in England remain stubbornly high, driven largely by older cohorts who have drunk heavily for decades, the trajectory among under-35s is genuinely improving. NHS England has noted a meaningful fall in alcohol-related A&E attendances among younger patients in recent years. The policy question is whether government should be actively accelerating this shift through minimum unit pricing, advertising restrictions or tax incentives for low-alcohol products, or whether the market is doing the work without intervention.

    Sober socialising as identity, not abstinence

    Perhaps the most significant cultural shift is semantic. Sobriety used to carry a narrative of struggle: recovery, willpower, the giving up of something. That framing has largely broken down among younger Britons. Increasingly, not drinking is framed as a positive identity, something you choose rather than something you endure. Sober bars have opened in Manchester, London and Bristol. Sober dating apps have attracted substantial user bases. “Mindful drinking” events sell out weeks in advance.

    This reframing matters enormously for how public health messaging gets constructed. Campaigns that emphasise sacrifice and self-denial have never performed particularly well. Campaigns that speak to performance, clarity, skin health and live-longer thinking connect with a generation that has already bought into wellness culture as an aspiration rather than a chore. It is worth reading alongside the broader longevity economy, in which consumers are spending freely on anything that credibly promises more years of quality life.

    What comes next for the no and low category

    The market shows no sign of plateauing. Innovation is accelerating. Functional drinks infused with adaptogens, nootropics and botanicals are positioning themselves as genuine alternatives rather than compromises. Several craft breweries, including Beavertown and Brewdog, now generate a meaningful proportion of their revenue from alcohol-free lines. Supermarket own-brand no and low ranges have cut price points enough to make the category accessible well beyond the premium tier.

    For those already embedded in the wellness-first lifestyle, suppliers like HealthPod Mansfield, which offers tools specifically designed to support health, recovery and the kind of be-healthy philosophy that drives sober living choices, find themselves with a natural audience. People who have stopped drinking to recover faster, sleep better and live longer are precisely the customers seeking out red light therapy beds and supplementation regimes alongside their alcohol-free craft lager.

    Britain has not gone teetotal. The local pub, the wine with dinner, the celebratory glass of something fizzy: none of these are disappearing. But the no and low alcohol UK trend 2026 has permanently altered the default. A third of any given social gathering now involves at least one person who is not drinking, and they are no longer the odd one out. They are, increasingly, the ones who ordered the most interesting thing on the menu.

    Frequently Asked Questions

    How big is the no and low alcohol market in the UK in 2026?

    The UK no and low alcohol sector was valued at approximately £224 million in 2023 and has grown substantially since, driven by rising demand from younger consumers and the expansion of premium brands like Seedlip, Lucky Saint and Lyre’s. Major supermarkets have significantly increased shelf space dedicated to the category.

    Why are younger people in the UK drinking less alcohol?

    Research consistently points to a combination of mental health awareness, cost sensitivity and a broader shift towards wellness-focused lifestyles. Among 16 to 24-year-olds, abstinence rates have roughly doubled since the early 2000s, with many choosing sobriety as a performance and wellbeing strategy rather than for moral or religious reasons.

    Are pubs losing money because of the no and low alcohol trend?

    It is complicated. Pubs that have not adapted their offer face genuine margin pressure, since alcohol historically drives hospitality profitability. However, operators who have invested in credible no and low menus report that sober and mindful-drinking customers often spend more per head on food and stay longer, partially offsetting the loss in alcohol revenue.

    What are the best no and low alcohol alternatives available in the UK?

    Premium options include Seedlip distilled non-alcoholic spirits, Lucky Saint alcohol-free lager, Lyre’s range of spirit alternatives and Beavertown Lazer Crush. Most major supermarkets including Waitrose, M&S and Tesco now stock extensive own-brand and premium ranges across beer, wine and spirits categories.