Author: Sophie Davis

  • The Quiet Collapse of the Office: What Commercial Real Estate’s Crisis Means for City Centres

    The Quiet Collapse of the Office: What Commercial Real Estate’s Crisis Means for City Centres

    Something quietly seismic is happening beneath the glass-and-steel skylines of London, Manchester, and every other city that built its identity around the nine-to-five. Office buildings, those totems of postwar economic confidence, are emptying out. Not temporarily, not seasonally, but structurally. The commercial real estate crisis gripping urban property markets is no longer a pandemic hangover. It is a permanent reckoning, and very few people in power seem prepared for what comes next.

    Occupancy data tells the story bluntly. According to research published by Savills and corroborated by data from the British Property Federation, average office utilisation across central London sits at roughly 40 to 50 per cent on any given weekday. Tuesday through Thursday see the highest footfall; Monday and Friday might as well be bank holidays for the average city-centre office. This is not a temporary blip. Lease renewal cycles are confirming it. Firms are downsizing their footprints at an extraordinary rate, taking less space, demanding higher quality, and simply walking away from anything built before 2010.
    Empty office towers in the City of London reflecting the commercial real estate crisis
    Empty office towers in the City of London reflecting the commercial real estate crisis

    Why Office Occupancy Has Structurally Changed

    The instinct is to blame remote working, and remote working certainly deserves its share of the credit. But that explanation flatters corporate leadership and misses the deeper forces at play. The truth is that the commercial real estate crisis was already brewing before March 2020. Technology had been quietly eroding the necessity of physical co-location for years. The pandemic simply compressed a decade of change into eighteen months.

    What firms discovered was not that offices were unnecessary, but that they were over-provisioned. The standard of roughly one desk per employee, multiplied across vast open-plan floors, was a legacy of a world where presence was the only proxy for productivity. That world is gone. Most knowledge-economy employers now operate on the assumption that staff will be in the office two or three days a week. The arithmetic is brutal: if your workforce attends at 50 per cent capacity, you need roughly half the space. And in cities where prime office rents run at £70 to £100 per square foot per annum, half the space is a very appealing proposition.

    What’s Happening to London’s Office Market Right Now

    London’s commercial property market is experiencing stress at a scale not seen since the early 1990s. The City of London, Canary Wharf, and even parts of the West End are contending with rising vacancy rates, falling valuations, and a widening gulf between prime and secondary stock. Grade-A offices with excellent environmental credentials, flexible floor plates, and excellent transport links are still being let. Everything else is struggling.

    Canary Wharf has become the most visible symbol of the commercial real estate crisis in Britain. HSBC’s decision to vacate its headquarters tower and consolidate into a smaller footprint in the City sent an unmistakable signal. The Wharf’s owners, the Canary Wharf Group, entered a debt restructuring process in 2024, and the long-term fate of several towers remains genuinely uncertain. This is not a peripheral story. It is happening at the heart of one of the world’s foremost financial districts.

    Further afield, cities like Manchester, Birmingham, and Leeds are experiencing similar pressures, though the dynamics differ. Regional office markets never commanded the same rental premiums as London, which means the correction is less dramatic in headline terms but potentially more damaging to local authority finances that depend on business rates from commercial property. According to the ONS commercial property price statistics, capital values across the UK office sector have declined materially since 2022, with secondary stock bearing the sharpest losses.
    Vacant commercial property window detail illustrating the commercial real estate crisis in UK cities
    Vacant commercial property window detail illustrating the commercial real estate crisis in UK cities

    The Investor Reckoning: Pension Funds and the Problem of Stranded Assets

    For investors, the commercial real estate crisis raises questions that extend well beyond property portfolios. Pension funds, life insurers, and property investment trusts hold billions of pounds in office assets. Much of that was acquired at valuations reflecting a pre-2020 world of full occupancy and steady rental growth. Those valuations are being revised downward, sometimes sharply.

    The concept of stranded assets, borrowed from climate finance, is increasingly useful here. A building that cannot be let because it fails modern sustainability requirements, lacks the flexibility tenants demand, or sits in a location that has simply lost its draw, is effectively stranded. It has a book value, but the market will not pay it. Investors holding these assets face an unpleasant choice: spend heavily on retrofit and repositioning, accept a heavily discounted sale, or wait and hope the market recovers. Most evidence suggests that waiting is not a strategy.

    The same logic applies to lenders. UK banks and overseas institutions that provided debt against commercial property on generous terms during the low-interest-rate years of the 2010s are now staring at loan books where collateral values have deteriorated. The Bank of England has flagged commercial real estate as a source of financial stability risk in successive Financial Stability Reports. This is not alarmism. It is the quiet, measured language of institutional concern.

    Could Conversion Be the Answer?

    The obvious question, the one mayors, planners, and property developers all reach for, is whether redundant office buildings can be converted into housing. It is an appealing idea. Britain has a chronic housing shortage and a surplus of empty office space. Surely those two problems cancel each other out.

    In practice, the arithmetic is considerably messier. Office floors designed for open-plan working often lack the structural depth, natural light penetration, and floor-to-ceiling height that residential conversions require. Central heating, plumbing, and fire safety standards for residential use are entirely different from commercial specifications. Many city-centre office blocks, particularly post-1960s curtain-wall buildings, are genuinely difficult and expensive to convert into habitable flats. Planning permissions add further complexity; permitted development rights allow some conversions without full planning consent, but local authorities in London and other major cities have frequently sought to restrict these rights to protect commercial land supply.

    That said, successful conversions are happening. Former office blocks in Bristol, Leeds, and parts of east London have become residential schemes, sometimes with genuinely innovative design. The government’s recent push to streamline planning for office-to-residential conversion has added momentum. Firms managing these projects increasingly rely on digital tools to coordinate communications across large project teams, and even niche utilities like an email tester become useful when checking that stakeholder notification systems are working correctly across complex multi-party developments.

    The City Centre Identity Crisis

    Beyond the investment mathematics, the commercial real estate crisis poses a subtler but equally serious challenge: what is a city centre for, if not offices? The entire ecosystem of the urban core, sandwich shops, dry cleaners, coffee concessions, pubs at lunchtime, the whole fabric of weekday commercial life, was built around the assumption of mass daily commuting. Remove that critical mass of workers and the economic logic of the city centre begins to unravel.

    This is already visible on the streets. Footfall data from the Centre for Cities think tank consistently shows that major UK city centres have not returned to pre-pandemic weekday pedestrian numbers. The recovery has been led by leisure and evening economy uses rather than work-related footfall. That is not necessarily fatal to city centres, but it requires a fundamental rethink of how urban space is programmed, funded, and maintained.

    The commercial real estate crisis is, ultimately, a forcing function. It is obliging planners, investors, and politicians to ask questions about urban form that should have been asked decades ago. What kind of city do we want to build? How much space should be dedicated to work, to living, to culture, to nature? The answers will vary by place. But the era of the office monoculture, entire city blocks given over entirely to desk-based employment, is drawing to a close. What replaces it will define the next chapter of British urban life.

    Frequently Asked Questions

    Why are office vacancy rates so high in London right now?

    Hybrid and remote working has permanently reduced the number of days employees attend offices, meaning firms need significantly less space than before. Many organisations are downsizing into smaller, higher-quality premises when leases expire, leaving older or less well-located buildings chronically underoccupied.

    How does the commercial real estate crisis affect UK pension funds?

    UK pension funds and property investment trusts hold significant allocations to office assets, many acquired at pre-2022 valuations. As capital values fall and rental income becomes less reliable, these funds face potential write-downs, reduced distributions, and difficult decisions about whether to sell, hold, or invest in expensive refurbishments.

    Can empty office buildings in the UK be converted into housing?

    Some can, but it is far from straightforward. Buildings designed for open-plan commercial use often have structural, lighting, and ventilation challenges that make residential conversion costly. Permitted development rights allow certain conversions without full planning consent, though London and several other councils have restricted these rights in designated commercial zones.

    Which UK cities are most affected by falling office demand?

    London, particularly Canary Wharf and parts of the City, has seen the most prominent distress, but Manchester, Birmingham, and Leeds are also contending with rising secondary vacancy rates. Regional cities face a different challenge in that their lower rental base leaves less room to absorb value declines without triggering loan covenant breaches.

    What happens to local economies when office buildings empty out?

    Reduced weekday footfall hits the surrounding retail and hospitality businesses that depend on lunchtime and commuter trade. Local authority income from business rates also falls as commercial property values decline, creating pressure on public services. Planners are increasingly looking at mixed-use redevelopment and evening economy incentives to compensate.
  • The Slow Travel Revolution: Why Discerning Travellers Are Abandoning Packed Itineraries for Depth Over Distance

    The Slow Travel Revolution: Why Discerning Travellers Are Abandoning Packed Itineraries for Depth Over Distance

    There is a particular kind of exhaustion that only seasoned travellers recognise. The one that arrives not after a long journey, but after a meticulously scheduled one. Three cities in five days. A museum before breakfast, a flight before dinner. The photographs are extraordinary; the memories, oddly thin. Slow travel luxury 2026 has emerged as a direct and rather elegant rebuke to all of that.

    This is not a fringe movement. Among Britain’s more thoughtful, culturally literate travellers, the shift is palpable and, by most accounts, permanent. The question is no longer how many places you can fit into a fortnight, but how deeply you can inhabit one. Depth over distance, as the phrase goes, has become the defining principle of a new kind of luxury.

    A traveller contemplating the Alentejo landscape, embodying the slow travel luxury 2026 philosophy
    A traveller contemplating the Alentejo landscape, embodying the slow travel luxury 2026 philosophy

    What Is the Slow Travel Philosophy, and Why Is It Resonating Now?

    Slow travel, at its core, borrows from the broader slow movement that emerged from Carlo Petrini’s Slow Food manifesto in late-1980s Italy. Applied to travel, it advocates staying longer in fewer places, engaging with local rhythms rather than tourist schedules, and measuring the success of a trip by what you understand at the end of it rather than what you have ticked off. Whilst the concept has circulated in travel writing for over a decade, something shifted meaningfully in 2025 and 2026 to push it from pleasant idea to genuine cultural force.

    Part of the answer is post-pandemic recalibration. British travellers who spent enforced periods at home rediscovered the pleasure of noticing things slowly, paying attention to what is immediately around them. Part of it is environmental consciousness; staying in one place for two weeks produces a fraction of the carbon footprint that a multi-destination tour generates. And part of it is, frankly, the luxury market doing what it always eventually does: following genuine desire rather than manufactured aspiration. High-net-worth travellers, the kind who once collected Michelin-starred restaurants across four countries in a single trip, are increasingly choosing a single villa in the Alentejo for ten nights, with a private guide and a reading list curated by a local academic.

    The Destinations Leading the Slow Travel Movement in 2026

    Not every place lends itself to the slow travel ideal. The best destinations share certain qualities: genuine local culture that rewards attention, landscapes that change with the light, food that is tied to place rather than trend, and enough quiet that you can hear yourself think.

    Portugal’s Alentejo region remains, by most measures, the spiritual home of slow travel luxury in 2026. Its cork forests, medieval hilltop towns and sparse, amber-lit plains feel designed for contemplation. Properties such as Herdade do Esporão have developed extended-stay programmes centred on viticulture, agricultural heritage and serious gastronomy. You arrive expecting a holiday and leave with something closer to an education.

    Japan’s Tohoku region, long overshadowed by Kyoto and Tokyo on the standard itinerary, has attracted substantial attention from discerning travellers seeking the country’s quieter self. Ryokan stays of a week or longer, centred on particular craft traditions such as Aizu lacquerware or Tsugaru shamisen music, have become genuinely sought-after experiences. The point is not observation but participation.

    Handcrafted ceramics and local produce reflecting the slow travel luxury 2026 attention to detail
    Handcrafted ceramics and local produce reflecting the slow travel luxury 2026 attention to detail

    Closer to home, Scotland’s far north has quietly become a destination of remarkable depth for slow travellers. The Orkney archipelago, in particular, offers something almost nowhere else can: a landscape that contains 5,000 years of human history, severe and luminous weather, and a local community of artists, farmers and archaeologists whose work is inseparable from the terrain. Several independent properties now offer week-long residencies built around the islands’ creative and academic communities. The scenery is, of course, spectacular. But scenery alone does not sustain a slow traveller; context does.

    Why Slow Travel and Luxury Are, in Fact, Natural Partners

    There is a common misconception that slow travel is austerity travel, that it means budget accommodation and a deliberate rejection of comfort. The opposite tends to be true at the upper end of the market. True slow travel luxury in 2026 is expensive precisely because it requires extraordinary quality at every point of sustained contact. One spectacular dinner is a treat; ten consecutive brilliant meals require a chef, a network of local producers and genuine culinary intelligence. One beautiful bedroom is easy to find; a space you can genuinely live in for a fortnight demands curation of an entirely different order.

    The most sophisticated slow travel operators understand this. Scott Dunn, the British luxury travel specialist, has reported significant growth in extended single-destination bookings over the past eighteen months, with clients increasingly requesting programmes that include private tutors, local mentors and curated cultural immersions rather than conventional excursions. The measure of success has shifted from novelty to understanding.

    This also represents a meaningful redefinition of exclusivity. In a world where most wealthy travellers have been everywhere, having been nowhere thoroughly is, perversely, the more distinguished position. To have spent three weeks in one Umbrian valley, to know the name of the farmer who produces your olive oil and the history of the church you walked past each morning, is a form of knowledge that no amount of itinerary-hopping can replicate.

    The Environmental Case, Which Is Impossible to Ignore

    Slow travel is not an environmental panacea, and it would be intellectually dishonest to pretend otherwise. Flying to Portugal and staying for three weeks still involves a flight to Portugal. But the arithmetic is notably better than flying to five destinations across a fortnight, and the emerging class of slow travellers is increasingly supplementing or replacing flights with long-distance rail journeys. The BBC’s science and environment coverage has consistently noted that aviation accounts for roughly 2.5 per cent of global CO2 emissions but a far higher share of effective climate warming when contrasted effects are included. Reducing flight frequency matters, even when total travel remains high.

    The overland renaissance is a significant subplot of the slow travel story. The Caledonian Sleeper from London to Inverness, the Venice Simplon-Orient Express, and a growing number of premium rail routes across Europe have attracted travellers who once would have flown without a second thought. The journey, in the slow travel model, is not an inconvenience to be minimised but a first act of the experience itself.

    How to Actually Do Slow Travel Well

    The practical barriers are real. Most Britons receive between 25 and 28 days of annual leave; a fortnight in one place feels extravagant to many. But slow travel need not mean extended sabbaticals. A long weekend in one Yorkshire village, properly engaged with, produces more lasting memory than four European capitals in a week. The philosophy scales.

    For those planning a genuine immersive trip, the principles are straightforward. Arrive without a checklist. Identify two or three things you genuinely want to understand, whether that is the local textile tradition, a regional cooking technique, or the history of a particular landscape, and build your time around those. Stay somewhere that feels like habitation rather than accommodation. Eat with the rhythm of local life. Walk more than you think necessary. Resist the hotel’s activity programme unless it genuinely interests you.

    The slow travel movement, at its best, is simply an argument for taking seriously the places we choose to visit. It asks travellers to bring their full attention rather than their best luggage. In a world that accelerates almost everything by default, that particular kind of deliberateness feels, unexpectedly, like the most radical luxury of all.

    Frequently Asked Questions

    What does slow travel actually mean in practice?

    Slow travel means staying in fewer destinations for longer periods, prioritising genuine engagement with local culture, food and landscape over ticking off attractions. Rather than visiting five countries in a fortnight, a slow traveller might spend ten days in a single region, building real knowledge of the place rather than a curated highlight reel.

    Is slow travel luxury more expensive than conventional luxury holidays?

    Extended stays of genuine quality tend to cost more in absolute terms, simply because high standards must be maintained over a longer period. However, per-day costs can be lower, and many travellers find the value proposition far superior, as the depth of experience is incomparably richer than a succession of brief, expensive stops.

    Which are the best slow travel destinations for British travellers in 2026?

    Portugal’s Alentejo, Japan’s Tohoku region and Scotland’s Orkney archipelago are among the most compelling options for culturally serious slow travellers this year. Each rewards extended attention with layers of history, food culture and landscape that a short visit cannot hope to reach.

    Is slow travel actually better for the environment?

    It is generally more environmentally efficient than multi-destination travel, as it reduces the total number of flights taken. Combining slow travel with overland rail options, such as the Caledonian Sleeper or European train routes, reduces the carbon impact further, though a transatlantic flight remains significant regardless of how long you stay.

    Can slow travel work with a standard British annual leave allowance?

    Absolutely. The principles of slow travel apply at any scale; a long weekend spent properly exploring one part of the English countryside is slow travel in spirit. For those planning longer trips, combining annual leave with bank holidays strategically can create ten to twelve day windows that work well for genuinely immersive experiences.

  • Quantum Computing Just Became Real: What Every Business Needs to Know in 2026

    Quantum Computing Just Became Real: What Every Business Needs to Know in 2026

    For years, quantum computing occupied the same intellectual territory as fusion energy and human teleportation: endlessly promising, perpetually distant, and deeply convenient to ignore. That era is over. The quantum computing business impact in 2026 is no longer a matter of projection, it is a matter of preparation, and a significant number of British and European enterprises are already behind.

    What changed? In short: hardware stabilised, error correction made meaningful progress, and the major commercial players stopped waiting for perfection before deploying. IBM, Google, and a cohort of well-funded European challengers including Oxford-based Quantum Motion have moved from demonstration to early commercial access. The question is no longer whether quantum advantage is real. It is whether your sector is about to feel it first.

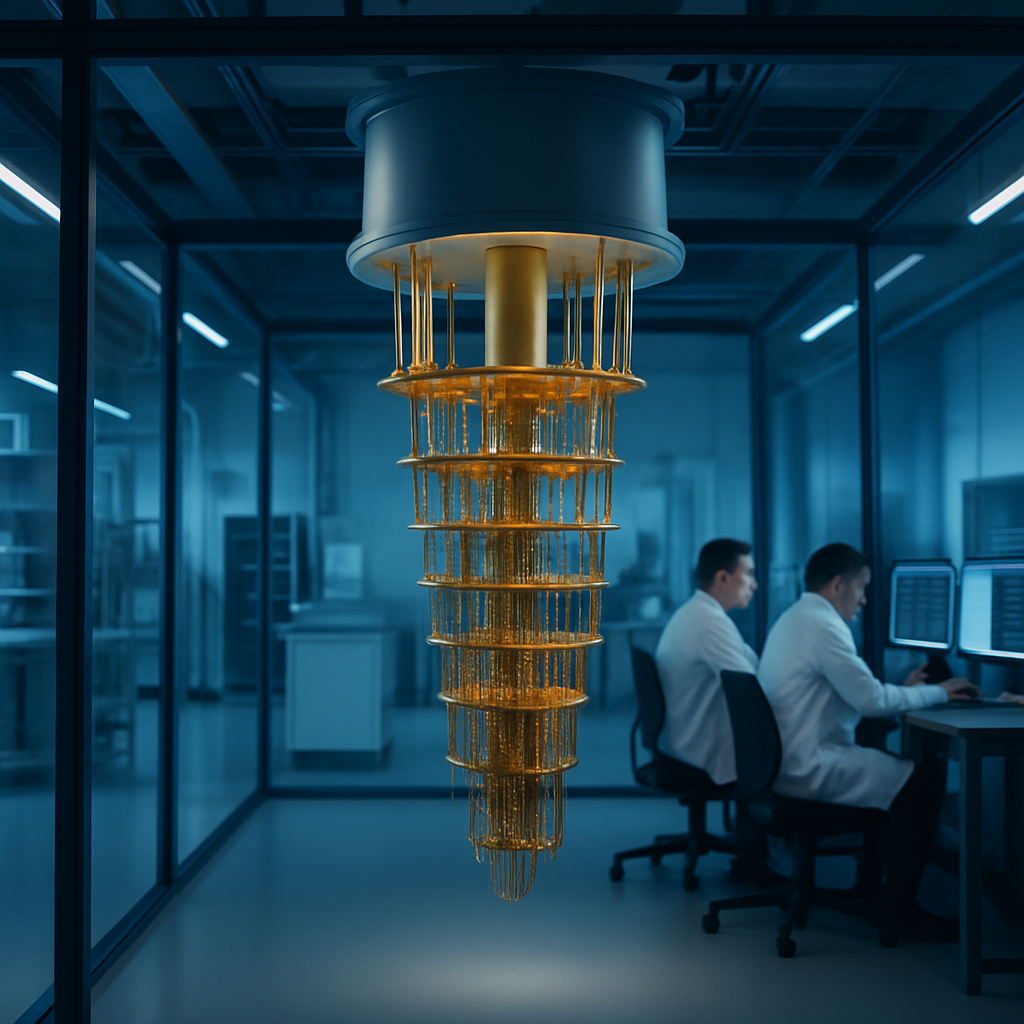
    Quantum computing business impact 2026, cryogenic quantum processor in a British research facility
    Quantum computing business impact 2026, cryogenic quantum processor in a British research facility

    What Does “Quantum Advantage” Actually Mean in Practice?

    The term gets thrown around with remarkable looseness. Quantum advantage, in its proper sense, describes the point at which a quantum computer solves a specific, commercially relevant problem faster or more accurately than any classical computer could, at a cost that makes deployment worthwhile. Notice the specificity. Quantum machines are not general-purpose replacements for the servers humming in data centres across the country. They are extraordinary at certain categories of problem: optimisation, simulation, and factorisation. Everything else, for now, remains firmly in classical territory.

    That distinction matters enormously when you are trying to assess risk or opportunity for your organisation. The businesses that will extract early value are those operating in domains where those three problem types are central. The businesses that should be most alarmed are those whose security infrastructure depends on the difficulty of factorisation. Which brings us directly to cybersecurity.

    The Cybersecurity Time Bomb: Harvest Now, Decrypt Later

    Britain’s National Cyber Security Centre (NCSC) has been direct about the threat. Adversaries are already harvesting encrypted data today, with the explicit intention of decrypting it once sufficiently powerful quantum machines become accessible. Government communications, financial records, medical histories, intellectual property: all of it potentially exposed to a retrospective breach that hasn’t technically happened yet but functionally already has.

    The NCSC’s guidance on post-quantum cryptography migration is not aspirational reading material for the future. It is an active operational priority. Organisations subject to UK regulatory frameworks, whether through the FCA, ICO, or sector-specific requirements, should treat their cryptographic estate as a live vulnerability. The migration to quantum-resistant algorithms is neither cheap nor swift; starting in 2026 is late, not early. You can read the NCSC’s post-quantum cryptography guidance directly at ncsc.gov.uk.

    Finance: Portfolio Optimisation and Risk Modelling at Unprecedented Scale

    The City has been watching quantum computing closely since at least 2019, and with good reason. Financial modelling is, at its core, an optimisation problem of extraordinary complexity. Pricing derivatives, stress-testing portfolios across thousands of correlated variables, detecting fraud patterns in real time, these tasks currently consume enormous classical computing resources and still return approximations rather than optima.

    Early quantum advantage in finance does not mean quantum computers replacing Bloomberg terminals next quarter. It means that within a narrow but high-value band of calculations, particularly Monte Carlo simulations and portfolio rebalancing at scale, hybrid quantum-classical systems are already demonstrating measurable improvements in speed and accuracy. HSBC and Barclays have both disclosed research partnerships in this space. For smaller asset managers and fintechs, the practical implication is that competitive edge will accrue to whoever integrates quantum-enhanced analytics first, even through cloud-based access rather than on-premises hardware.

    Quantum computing business impact on financial modelling and portfolio optimisation in 2026
    Quantum computing business impact on financial modelling and portfolio optimisation in 2026

    Pharmaceuticals: The Industry With the Most to Gain

    Arguably no sector stands to benefit more profoundly from genuine quantum computing business impact in 2026 and beyond than pharmaceuticals. Drug discovery is, fundamentally, a molecular simulation problem. Classical computers can model small molecules with reasonable accuracy, but the moment you move to the complex protein interactions relevant to most serious disease targets, the computational cost becomes prohibitive. Quantum computers simulate quantum systems natively, which is precisely what molecular chemistry is.

    AstraZeneca has publicly discussed quantum computing partnerships, and the wider UK life sciences sector, which contributes over £94 billion annually to the economy according to the Office for National Statistics, has strong strategic reasons to move quickly. A meaningful reduction in the time and cost of identifying viable drug candidates would be transformative. Early estimates suggest quantum-assisted drug discovery could compress certain phases of the development pipeline by years, not months. At a time when NHS procurement pressures and global health challenges demand faster therapeutic pipelines, the stakes are substantial.

    Logistics: The Optimisation Problem That Never Ends

    Supply chain optimisation is a domain where quantum advantage is already beginning to manifest in proof-of-concept work. Route planning, warehouse allocation, demand forecasting across complex multi-supplier networks: these are all variants of what mathematicians call the travelling salesman problem, notorious for its exponential classical complexity.

    For major British retailers and logistics operators, think the scale of Royal Mail, Tesco’s distribution network, or the Port of Felixstowe’s throughput management, even marginal improvements in routing efficiency translate into millions of pounds annually. Quantum optimisation is unlikely to replace classical logistics software wholesale, but as a supplementary layer applied to the hardest optimisation decisions, the value proposition is increasingly credible. Several UK logistics firms are already engaged in pilot programmes through IBM’s Quantum Network and similar platforms.

    What Should British Business Leaders Actually Do Right Now?

    The honest answer is: it depends entirely on your sector, your data sensitivity, and your competitive position. For most organisations, a two-track approach makes sense. The first track is defensive: audit your cryptographic infrastructure, begin understanding post-quantum migration requirements, and engage your IT security leadership on a realistic timeline for compliance. The second track is exploratory: identify the specific optimisation or simulation problems in your operations where quantum advantage might eventually apply, and begin building the internal literacy to evaluate vendor claims intelligently.

    Vendor claims, incidentally, deserve healthy scepticism. The gap between a press release announcing a quantum breakthrough and a deployable commercial solution remains wide in most cases. The organisations that will navigate this well are those that neither dismiss quantum as distant science fiction nor rush to expensive commitments based on hype. Informed, deliberate engagement is the appropriate posture.

    Britain’s Quantum Ambitions and the Stakes for UK Plc

    The UK government committed £2.5 billion to its National Quantum Strategy in 2023, with significant tranches being deployed through 2026 via Innovate UK and the Engineering and Physical Sciences Research Council. Britain has genuine world-class capability in this field: the universities of Oxford, Cambridge, and Bristol rank amongst the leading quantum research institutions globally.

    Whether that academic excellence converts into commercial leadership is the defining question. The quantum computing business impact in 2026 is real, targeted, and accelerating. The industries most exposed to disruption and most positioned for advantage have been identified. The window for deliberate preparation, rather than reactive scrambling, is still open. Just not indefinitely.

    Frequently Asked Questions

    What is quantum computing business impact in 2026 actually referring to?

    It refers to the practical, commercial effects of early quantum advantage becoming accessible to businesses across sectors including finance, pharmaceuticals, logistics, and cybersecurity. In 2026, this means hybrid quantum-classical systems delivering measurable improvements in specific high-complexity tasks, rather than wholesale replacement of existing computing infrastructure.

    Should UK businesses be worried about quantum computing breaking their encryption?

    Yes, with appropriate urgency rather than panic. The NCSC has issued guidance on post-quantum cryptography migration, acknowledging that adversaries may already be harvesting encrypted data for future decryption. Any UK organisation holding sensitive data under FCA, ICO, or similar regulatory frameworks should review their cryptographic estate now.

    How does quantum computing help the pharmaceutical industry?

    Quantum computers can simulate molecular interactions natively, which is precisely what drug discovery requires. This could dramatically reduce the time needed to identify viable drug candidates and accelerate clinical pipeline development, with major implications for UK life sciences, which contributes over £94 billion annually to the economy.

    Do businesses need to buy quantum hardware to benefit?

    Not at all. Cloud-based quantum access through platforms like IBM Quantum Network, Microsoft Azure Quantum, and others allows organisations to run quantum algorithms without any on-premises hardware investment. This significantly lowers the barrier to early experimentation and pilot deployment.

    How does quantum computing differ from regular high-performance computing?

    Classical high-performance computing scales up conventional binary processing, using more and faster traditional processors. Quantum computing uses qubits that exploit superposition and entanglement to process certain problem types, particularly optimisation, simulation, and factorisation, in fundamentally different and far more efficient ways than any classical approach can.